
Blogs
PW Consulting: Single Point Anchor Reservoir Market Hits $1.42B in 2025, 5.45% CAGR to $2.06B by 2032
By pmarketresearch, 2026-09-16
Unlocking Strategic Value in the Global Single Point Anchor Reservoir Market: A 2026 Outlook
The global energy landscape is undergoing a profound transformation, driven by the dual imperatives of securing traditional hydrocarbon supplies and accelerating the transition to renewable offshore sources. In this complex environment, specialized infrastructure components play a pivotal role in enabling operational efficiency and safety. Our latest market study, Worldwide Single Point Anchor Reservoir Market, offers a comprehensive examination of this critical sector, providing stakeholders with the intelligence needed to navigate the forecast period from 2026 through 2032.
This report is not merely a collection of statistics; it is a strategic tool designed to inform capital allocation, risk management, and long-term technology roadmaps. As we look toward 2026, understanding the trajectory of Single Point Anchor Reservoirs becomes essential for developers, investors, and policy makers alike. The analysis presented herein bridges the gap between historical performance and future potential, grounding strategic decisions in robust data.
Market Trajectory and Growth Dynamics
The market for Single Point Anchor Reservoirs has demonstrated resilience and steady expansion over the past half-decade. Our analysis covers historical data from 2020 to 2025, establishing a reliable baseline for future projections. In 2020, the global market size was valued at USD 1089.45 Million. Since then, the sector has experienced consistent upward momentum, reaching an estimated USD 1420.5 Million in 2025.
Looking ahead, the forecast period indicates continued growth, albeit at a moderate pace reflective of broader industry maturation. The market is projected to reach USD 1446.25 Million in 2026, marking the beginning of a growth curve that extends to USD 2059.53 Million by 2032. This expansion corresponds to a Compound Annual Growth Rate (CAGR) of 5.45 percent over the forecast period. Such figures suggest a stable investment environment where growth is driven by incremental technological improvements and sustained demand across key application areas rather than volatile speculative spikes.
For enterprise decision-makers, this trajectory implies that the sector offers reliable opportunities for long-term engagement. The steady CAGR highlights a market that is evolving methodically, allowing organizations to plan infrastructure investments with a degree of certainty regarding future market size and liquidity.
Operational Scope and Segment Insights
Our research delves deep into the structural composition of the market to identify where value is being generated. The segmentation analysis provides clarity on the various technologies and deployment contexts that define the industry. By understanding the distribution of revenue across different types and applications, stakeholders can identify high-potential niches without relying on generalized assumptions.
The report examines the market by type, covering established technologies such as Truss Spar, Classic Spar, and Cell Spar configurations. Each configuration presents distinct engineering advantages and cost structures relevant to specific water depths and environmental conditions. Similarly, the application landscape is dissected to reveal how these reservoirs are utilized across Offshore Oil and Gas Production, Deepwater Drilling, and emerging sectors like Floating Offshore Wind Energy.
Demand is not evenly distributed across regions, and our geographic analysis maps the intensity of activity across North America, Europe, Asia Pacific, Latin America, and the Mideast and Africa. This spatial understanding is crucial for supply chain optimization and regional partnership development. While the core data provides specific valuations for each segment, our strategic briefing highlights the relative dominance of mature offshore regions versus emerging markets. Clients who access the full report gain the granular insight needed to prioritize regions that align with their risk tolerance and capacity capabilities.
Competitive Landscape and Market Concentration
The structure of the industry is characterized by a significant degree of consolidation, which has implications for market entry and partnership strategies. Our study indicates a moderately concentrated market environment. The top three firms hold a combined market share of 42.5 percent, while the top five players account for 61.25 percent of the total revenue.
Worldwide Single Point Anchor Reservoir Market
This concentration level suggests that while there is room for specialized niche players, the bulk of the market volume is controlled by established incumbents with significant resources. For new entrants or expanding competitors, this landscape necessitates a clear value proposition, whether through cost innovation, specialized engineering capabilities, or strategic alliances with major operators. The report profiles key companies operating in this space, analyzing their positioning, recent developments, and strategic moves.
Understanding the behavior of these dominant players is critical for anticipating pricing trends, supply chain dynamics, and technology licensing opportunities. Our analysis provides the context needed to benchmark internal capabilities against industry leaders and to identify gaps in the market that remain underserved by the major conglomerates.
Industry Dynamics and Strategic Drivers
Several macroeconomic and technological factors are shaping the demand for Single Point Anchor Reservoirs in the coming years. The persistence of offshore oil and gas production remains a primary driver, as operators seek to optimize existing fields and access deeper reserves where traditional fixed structures are impractical. The efficiency and stability offered by single point anchor systems make them a preferred choice for these challenging environments.
Simultaneously, the energy transition is introducing new vectors for growth. The expansion of Floating Offshore Wind Energy requires robust mooring and anchoring solutions that can withstand dynamic loads over long periods. As renewable infrastructure scales up, the technology overlap between traditional offshore anchoring and wind energy applications creates cross-sector opportunities for manufacturers and service providers.
Regulatory environments and environmental standards are also tightening, influencing design specifications and material choices. Companies must adapt to stricter compliance requirements regarding seabed impact and lifecycle sustainability. Our report integrates these regulatory considerations into the market outlook, ensuring that strategic plans account for compliance costs and potential barriers to entry.
The Strategic Value of Comprehensive Intelligence
In an era where data overload often obscures actionable insight, targeted intelligence is the differentiator between reactive management and proactive strategy. This Worldwide Single Point Anchor Reservoir Market study is designed to cut through the noise. It offers a detailed examination of the factors that will define success in 2026 and beyond.
Stakeholders who utilize this research will be better positioned to:
- Optimize capital expenditure planning based on verified growth trajectories.
- Identify high-growth segments within type and application categories before competitors.
- Understand the competitive intensity and concentration risks in target regions.
- Align technology development roadmaps with emerging demand drivers in both hydrocarbon and renewable sectors.
The global market size, growth rate, and regional distribution form the backbone of this analysis, but the true value lies in the synthesis of these elements into coherent strategic recommendations. By accessing the full dataset, organizations can move beyond surface-level trends and engage with the specific metrics that drive bottom-line performance.
Conclusion: Navigating the Future of Offshore Infrastructure
The path forward for the Single Point Anchor Reservoir market is one of steady evolution and opportunity. With a forecast CAGR of 5.45 percent and a projected market value approaching USD 2.06 Billion by 2032, the sector remains a vital component of the global offshore energy infrastructure. The balance between established oil and gas applications and the burgeoning wind energy sector provides a diversified basis for demand that mitigates reliance on a single commodity cycle.
However, realizing the potential of this market requires more than general awareness. It demands precise, data-backed insights into segmentation, competitive positioning, and regional nuances. Our report provides the foundation for this understanding, but the depth of detail required for specific operational planning is available in the full study.
We invite industry leaders, investors, and strategic planners to explore the complete findings of the Worldwide Single Point Anchor Reservoir Market research. By securing access to the full intelligence package, your organization can ensure that its 2026 strategy is built on a foundation of accuracy, depth, and foresight. The future of offshore anchoring is being written now, and the insights within this report are the compass needed to navigate it successfully.
Water Tank Market
For detailed analysis of this topic, please visit the official page: Worldwide Single Point Anchor Reservoir Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Global Cobalt Acetate Market to Hit $627.29M by 2032, 5.71% CAGR, Says PW Consulting
By pmarketresearch, 2026-09-16
Beyond the Catalyst: Strategic Intelligence for the Global Cobalt Acetate Solution Market (2026–2032)
The global cobalt acetate solution market stands at a critical inflection point. As industries balance volatile raw material costs, evolving regulatory frameworks, and shifting demand centers, the ability to navigate this landscape with precision is no longer optional—it is a strategic imperative. Our latest comprehensive market study, Worldwide Cobalt Acetate Solution Market , provides the analytical rigor and forward-looking intelligence required to transform uncertainty into competitive advantage. This article outlines the strategic value of the research for enterprise decision-makers operating across chemicals, materials, and advanced manufacturing sectors in 2026 and beyond.
A Market in Macro-Transition: Scale, Trajectory, and Structural Shifts
Drawing on a robust historical baseline spanning 2020 through 2025 and a forward-looking forecast window extending to 2032, the analysis captures a market that has demonstrated remarkable resilience amid macroeconomic headwinds. Total market revenue has expanded steadily from the early 2020s, crossing the threshold of approximately $425.5 million in the base year of 2025 and accelerating toward $461.0 million in 2026. The forecast trajectory projects sustained growth, with the market expected to surpass half a billion dollars by the late 2020s and approach nearly $630 million by 2032, reflecting a compound annual growth rate of 5.71 percent.
This growth is not merely a function of volume expansion; it is deeply intertwined with structural realignment in end-use demand, regional supply chain reconfiguration, and the premiumization of product grades. Decision-makers evaluating capital allocation, procurement strategies, or market entry must understand how these macro-trends interact with segment-specific dynamics, inventory positioning, and pricing elasticity across the value chain.
Decoding the Competitive Architecture
The cobalt acetate solution ecosystem is shaped by a diverse set of players spanning integrated mining and refining corporates, specialized chemical manufacturers, and regional producers with distinct geographic footprints. Market concentration metrics indicate a moderately fragmented but increasingly consolidated landscape, where first-mover advantages in capacity expansion, regulatory compliance, and grade differentiation are actively reshaping competitive positioning.
Leading firms such as Umicore N.V. have reinforced their foothold through tailored high-purity grades and continuous regulatory alignment, exemplified by recent ECHA approvals that broaden permitted application scopes. Shepherd Chemical Company and Palm International maintain strong presences in the United States, emphasizing customization, packaging flexibility, and reliable logistics for industrial and specialty applications. Across Asia Pacific, players including Mechema Chemicals International, Coremax Corporation, and Zhejiang Huayou Cobalt have scaled production capabilities to serve catalysis, fiber, and industrial demand, while India-based manufacturers such as Muby Chemicals and RK Metkam Industries continue to expand export-oriented supply lines. Meanwhile, large integrated entities like China Molybdenum Co., Ltd. and Freeport Cobalt are positioning themselves to capture value further downstream through on-site or adjacent processing investments.
Understanding the strategic intent, capacity trajectories, and regulatory posture of these incumbents is essential for benchmarking, partnership evaluation, and competitive threat assessment.
Worldwide Cobalt Acetate Solution Market
Operational Intelligence: What the Report Delivers
This study is engineered to translate high-level market signals into actionable operational insights. Beyond headline sizing, the report delivers a multi-dimensional dissection of demand drivers, supply constraints, and commercial dynamics across key industrial verticals and geographic corridors. Topics examined in depth include:
- Application-led demand patterns across catalysis, coatings, surface finishing, advanced materials, and specialty chemical formulations, with qualitative discussion of substitution risk and performance thresholds
- Grade-level considerations distinguishing industrial-grade volumes from reagent and analytical-grade requirements, including purity specifications, packaging norms, and customer segmentation
- Production footprint analysis covering regional manufacturing capabilities, logistics considerations, and the impact of feedstock availability on capacity utilization
- Regulatory and compliance dimensions, including evolving chemical substance evaluations and the operational implications of registration updates on market access and product qualification
- Pricing and cost-structure dynamics tied to cobalt feedstock movements, including how metal and hydroxide price volatility propagates through conversion economics
- Competitive benchmarking frameworks to support market share assessment, partnership due diligence, and M&A screening
Each section is structured to support scenario planning, procurement strategy refinement, and revenue forecasting under varying macroeconomic and regulatory assumptions.
Forging Strategy in a Volatile Raw Material and Regulatory Environment
Cobalt acetate solution economics are highly sensitive to upstream conditions. Feedstock availability and pricing have exhibited pronounced swings, with cobalt metal prices more than doubling during 2025 and entering 2026 at elevated levels near $56,414 per metric ton, while hydroxide feed costs also experienced substantial escalation. These shifts have implications for conversion margins, contract structures, inventory hedging, and supplier selection. At the same time, regulatory developments are reshaping permissible use cases and compliance burdens, particularly in European markets where registration dossier updates and broader substance evaluation roadmaps continue to evolve.
Cobalt Market
Export policy adjustments in major producing regions have further influenced global supply balancing, prompting reassessment of sourcing diversification and regional inventory strategies. In this context, a disciplined intelligence framework becomes indispensable. The report integrates these dynamics into a coherent narrative, helping stakeholders evaluate exposure, stress-test supply assumptions, and identify mitigation pathways before disruptions crystallize into margin erosion or supply gaps.
Recent company-level developments underscore the pace of structural change. Capacity additions and product line upgrades have been announced and commissioned across multiple geographies, with some producers expanding lines dedicated to catalyst and pharmaceutical-adjacent grades, while others pursue enhanced-purity specifications for electronics and specialty intermediates. These moves are not isolated; they signal a broader industry-wide push toward grade differentiation, nearer-term capacity responsiveness, and tighter integration with downstream qualification requirements. Decision-makers who map these developments against their own sourcing and product roadmaps will be better positioned to anticipate shifts in availability, negotiate favorable terms, and align product portfolios with emerging demand pockets.
Why This Research Matters for 2026 Decision-Making
The forecast period through 2032 represents a window in which strategic choices made in 2026 will compound over time. Procurement leaders can use the analysis to calibrate contract structures, evaluate supplier resilience, and align volume commitments with realistic demand trajectories. Commercial teams can identify application segments with the strongest growth momentum and prioritize technical sales resources accordingly. Corporate development and strategy functions can leverage the competitive and regional mapping to screen partnership opportunities, assess market entry feasibility, and inform capital deployment decisions.
Equally important, the study provides the contextual framing necessary to separate noise from signal. Where market commentary often oscillates between optimism and pessimism, a structured, data-anchored approach clarifies which trends are durable and which are cyclical. That clarity is critical for setting realistic targets, managing stakeholder expectations, and building agile strategies that can adapt as feedstock markets, regulatory environments, and demand patterns evolve.
Secure the Complete Intelligence Package
This article offers a strategic preview of the themes, drivers, and structural forces shaping the global cobalt acetate solution market. To move from orientation to execution, decision-makers need the full analytical depth of the worldwide market study, including detailed segmentation discussions, regional and application-level context, competitive profiles, and forward-looking scenario analysis. The complete report is available through our official research portal, where you can access the full dataset, methodology overview, and executive summaries tailored to your organizational priorities.
In a market defined by volatility, regulation, and rapid capacity evolution, informed decisions are the ultimate competitive moat. Equip your team with the intelligence required to navigate the next phase of market development with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Cobalt Acetate Solution Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Microscopy Targets Market Hits $285.75M in 2025, Poised to Reach $454.52M by 2032 with 6.85% CAGR
By pmarketresearch, 2026-09-16
Navigating Precision: Strategic Intelligence for the Microscopy Targets Market Through 2032
Executive Overview: Navigating the Precision Imperative
The microscopy targets market stands at a critical inflection point where foundational metrology meets accelerating technological adoption. As laboratory workflows, semiconductor inspection protocols, and advanced materials characterization converge, the demand for standardized, highly accurate calibration and resolution verification tools has evolved from a routine operational necessity to a strategic competitive differentiator. Our latest market research delivers a structured, forward-looking intelligence framework designed specifically to support enterprise decision-making during the 2026–2032 forecast window. This publication is engineered to clarify trajectory, quantify structural shifts, and equip leadership teams with the analytical rigor required to allocate capital, prioritize product development, and navigate an increasingly consolidated supplier landscape.
Market momentum is already evident in the historical record. From a baseline of approximately 182.45 million USD in 2020, the sector advanced through a series of compounding growth phases, reaching 285.75 million USD by 2025. The trajectory suggests sustained expansion rather than cyclical fluctuation, with the broader market projected to scale toward 454.52 million USD by 2032. Underlying this progression is a forecasted compound annual growth rate of 6.85 percent across the 2026–2032 evaluation period. These figures are not merely retrospective summaries; they are the structural scaffolding for scenario planning, capacity forecasting, and long-term investment alignment. Understanding how this growth distributes across technological categories, end-use domains, and geographic corridors requires a granular analytical lens—one that this report systematically provides while deliberately reserving proprietary segmentation intelligence for full-access consultation.
Structural Validation: Historical Trajectory and Forecast Architecture
The 2020–2025 analytical window captures a market that has absorbed multiple overlapping catalysts: heightened emphasis on quantitative imaging reproducibility, tighter metrology traceability requirements, and the gradual migration of advanced microscopy into high-throughput industrial and semiconductor workflows. The historical progression reflects both steady baseline demand and episodic acceleration tied to equipment refresh cycles and regulatory calibration expectations. Looking forward, the forecast architecture does not assume linear continuation. Instead, it layers sensitivity variables including instrumentation adoption curves, custom substrate engineering timelines, and regional capacity expansion patterns.
Strategic planners frequently encounter a common challenge in this sector: macroeconomic headline figures obscure the underlying distribution mechanics that actually drive procurement decisions. Revenue concentration patterns indicate that a relatively small group of manufacturers commands a substantial share of global supply, with the top three firms collectively representing approximately 48.5 percent of market revenue and the top five reaching roughly 62.3 percent. This concentration has meaningful implications for supplier diversification, pricing leverage, and technology access. The research framework deconstructs these dynamics without reducing them to oversimplified rankings, instead mapping how scale, fabrication capabilities, and certification infrastructure interact to shape competitive positioning. By embedding the 2026–2032 forecast within a structured scenario envelope, the report enables organizations to test internal assumptions against market-validated boundaries rather than extrapolating from isolated pilot data.
Commercial Architecture: Technology Categories, Application Domains, and Regional Corridors
Effective market positioning requires more than total revenue visibility. It demands clarity on how the product landscape fractures across functional use cases, how procurement priorities differ by domain, and where geographic demand clusters intersect with supply-side capabilities. The commercial architecture of this market can be understood through three interlocking dimensions: technology classification, application orientation, and regional deployment patterns. Each dimension carries distinct procurement economics, validation requirements, and innovation pacing.
Worldwide Coating Target Materials Market
At the technology layer, demand is anchored by several core product families that serve complementary but non-interchangeable functions. Stage micrometers remain foundational for routine dimensional verification and workflow calibration, while calibration reticles support higher-precision optical alignment and system benchmarking. Resolution targets occupy a more specialized tier, catering to performance validation for advanced imaging modalities where pattern fidelity and structural resolution are paramount. The interplay among these categories is not merely additive; it reflects evolving laboratory standardization practices and the gradual integration of custom micro- and nano-patterned substrates into quantitative imaging pipelines.
On the application side, procurement behavior diverges sharply by industry lifecycle, regulatory environment, and instrumentation density. Life sciences research continues to drive consistent baseline demand, particularly where reproducibility and quantitative phase measurement are becoming standard expectations. Materials science applications impose different performance criteria, emphasizing structural characterization and calibration reliability across varied sample morphologies. Semiconductor inspection introduces tighter tolerance thresholds and higher throughput expectations, reinforcing the need for targets that can withstand repeated verification cycles without degradation. Industrial quality control rounds out the application spectrum with use cases centered on repeatability, cost efficiency, and integration with existing inspection infrastructure. The report maps these application streams to procurement drivers and technology adoption pathways, providing decision-makers with a functional view of where demand is structurally anchored versus where it remains opportunistic.
Regional distribution further shapes competitive strategy. Demand concentration intersects with local metrology ecosystems, instrument manufacturing footprints, and certification accessibility. North American, European, and Asia-Pacific corridors each present distinct procurement rhythms and supplier engagement models, while Latin American and Middle East/Africa markets reflect more targeted, application-specific adoption patterns. The analysis preserves this geographic nuance while avoiding reductive regional breakdowns, instead emphasizing how regional demand interacts with supply-chain resilience, import dependencies, and localized calibration standards. For organizations evaluating expansion, partnership, or sourcing realignment, this layered perspective provides a practical starting point for market-entry prioritization without exposing the full segmentation matrix that forms the core of the paid intelligence package.
Competitive Dynamics and the Consolidation Imperative
The supplier landscape is defined by a blend of specialized instrumentation experts, precision fabrication specialists, and broad-distribution optics providers. Competitive advantage in this sector does not emerge from volume alone; it is increasingly determined by fabrication precision, certification readiness, and the ability to deliver customized calibration substrates at scale. Several recurring capability themes differentiate the players that are actively shaping market direction.
Leading suppliers are distinguished by their micro- and nano-patterning infrastructure. Companies leveraging electron-beam lithography and high-resolution patterning processes are positioning themselves at the upper end of the resolution envelope, with structural feature sizes reaching into the nanometer range. This capability directly supports advanced microscopy applications where conventional calibration tools no longer satisfy validation requirements. At the same time, broader-tier suppliers maintain market relevance through standardized test charts, chrome-on-glass patterning, and widely adopted resolution references that serve high-volume laboratory and industrial users. The coexistence of these approaches creates a market with multiple entry points but also rising expectations for calibration traceability and pattern reproducibility.
Beyond fabrication, certification and traceability have become central competitive signals. Stage micrometers and calibration standards increasingly require documentation aligned with recognized metrology frameworks, with traceability pathways connected to national calibration institutions and compliant quality systems. Suppliers that can demonstrate consistent certification processes, audit-ready documentation, and alignment with ISO expectations gain measurable advantage in regulated procurement environments. This dynamic is especially pronounced in applications where measurement integrity directly affects downstream analysis, including life sciences imaging and industrial quality control.
Competitive positioning is further shaped by recent ecosystem developments. In March 2026, ZEISS introduced a new VR-based microscopy training program developed in partnership with universities, focused on system components and workflow integration. While operating in a related instrumentation space, this initiative reflects a broader industry movement toward structured knowledge transfer, standardization of operational practices, and deeper alignment between equipment vendors, end users, and academic training pipelines. Training and workflow enablement are increasingly viewed as complements to hardware performance, reinforcing the importance of suppliers that can offer not only calibration targets but also the procedural context needed to deploy them effectively.
Against this backdrop, the market exhibits a clear consolidation dynamic. Scale players continue to consolidate supply advantages through broad product portfolios, established distribution channels, and recognized certification credentials. Specialized manufacturers, meanwhile, compete through custom engineering, advanced patterning, and domain-specific target design. The strategic question for buyers and investors alike is not simply who holds the largest share, but how the competitive architecture will evolve as fabrication precision becomes more accessible, certification expectations tighten, and end users demand tighter integration between calibration, training, and imaging workflows. The report provides a structured competitive mapping that highlights operational strengths, capability boundaries, and likely pressure points without flattening the landscape into a simple leaderboard.
Regulatory Anchors and Calibration Ecosystems
The credibility of microscopy targets is inseparable from the regulatory and standards environment that surrounds them. As quantitative imaging and high-resolution characterization become embedded in more critical workflows, calibration verification has shifted from optional best practice to operational expectation. Certified stage micrometers and calibration reticles are increasingly supplied with documentation that supports traceability claims and alignment with recognized quality frameworks. This is not a peripheral compliance issue; it is a core component of procurement justification in environments where measurement integrity directly affects research reproducibility, process validation, or inspection reliability.
Traceability expectations are particularly pronounced where calibration standards must be demonstrably connected to national metrology institutions. Certification pathways that support documented traceability reinforce confidence in measurement accuracy and reduce ambiguity in cross-site or cross-instrument comparison. In practice, this means the market is rewarding suppliers that can integrate fabrication precision with validation rigor, rather than treating certification as an afterthought. The research evaluates how these standards realities influence supplier selection, procurement cycle timing, and the commercial value of certification-ready product lines. This section is especially relevant for procurement teams seeking to align purchasing decisions with institutional quality requirements while avoiding hidden validation risks.
Strategic Utility for 2026 Decision-Making
This research is structured to translate market complexity into actionable strategic clarity. For executive teams, the report functions as a decision-support instrument across several core planning dimensions: revenue forecasting, product portfolio alignment, supplier diversification, and technology investment sequencing. Rather than presenting static snapshots, the analysis is designed to help organizations test assumptions, bound uncertainty, and identify where strategic intervention will yield the highest return.
In practice, the report supports 2026 decision-making through several concrete applications. First, it provides a market-validated growth context that can anchor internal projections and investment scenarios, allowing leadership to benchmark plans against an evidence-based trajectory rather than internal extrapolation alone. Second, it maps the structural relationships among product categories, application domains, and regional demand patterns, enabling more precise segmentation of addressable opportunity. Third, it examines the competitive field through capability-based lenses, helping organizations identify where supplier concentration creates vulnerability, where specialized partnerships can accelerate product validation, and where certification alignment is becoming a gatekeeping requirement. Fourth, it integrates regulatory and traceability dynamics into commercial analysis, clarifying why certain product lines command premium positioning and how compliance expectations shape procurement behavior.
The publication is deliberately constructed to balance depth with discipline. It delivers enough analytical rigor to establish credibility and demonstrate methodological precision, while preserving the core segmentation data, detailed company-level assessments, and granular forecast breakdowns for the full licensed research package. This approach ensures that readers gain a clear understanding of market architecture and strategic implications, while recognizing that precise percentage splits, regional revenue allocations, and application-specific volume estimates are reserved for the complete intelligence release. The intent is not to withhold insight, but to structure it in a way that supports executive evaluation while maintaining the commercial integrity of the proprietary dataset.
Scope of Operational Intelligence and Access Path
The full research package extends well beyond the structural overview presented here. It delivers operational-ready content designed for cross-functional use across strategy, product management, procurement, and market development teams. Core components include a detailed segmentation architecture that disaggregates market value across technology types, application verticals, and regional corridors, supported by historical baselines and forward projections through 2032. The report also incorporates supplier profiling, capability mapping, and technology differentiation analysis that connects fabrication methods, certification readiness, and product families to real-world commercial positioning.
Additional operational content covers procurement dynamics, validation expectations, and the practical implications of certification traceability for sourcing decisions. Scenario frameworks are included to help organizations evaluate demand sensitivity under differing adoption assumptions, equipment refresh cycles, and regulatory evolution paths. For teams evaluating entry, expansion, or partnership opportunities, the research provides the structural context necessary to prioritize where precision, scale, and certification alignment will matter most.
Microscopy Targets Market
Strategic readers seeking the complete segmentation matrix, district-level market allocations, application-specific revenue detail, and proprietary competitive benchmarking will find the full licensed version engineered for direct integration into planning workflows. The published excerpt establishes the analytical foundation and strategic relevance; the complete report converts that foundation into a deployable intelligence asset.
Conclusion
The microscopy targets market is expanding within a framework defined by rising precision expectations, increasingly formalized calibration standards, and a supplier landscape where scale and specialization are both influencing commercial outcomes. With historical growth establishing a durable trajectory and the 2026–2032 forecast signaling continued expansion toward a materially larger addressable base, the strategic window for aligned decision-making is open now. Organizations that understand the interplay between product categories, application demand, certification requirements, and competitive concentration will be better positioned to allocate resources, manage supplier risk, and capture value as the market matures. This research provides the structured intelligence necessary to make those decisions with confidence, while preserving the detailed segmentation intelligence for teams ready to convert insight into execution.
For detailed analysis of this topic, please visit the official page: Microscopy Targets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Paper Cup Sleeve Market to Hit $916.19M by 2032, 5.19% CAGR (2025-2032)
By pmarketresearch, 2026-09-16
Strategic Intelligence for 2026: Navigating the Worldwide Paper Cup Sleeve Market
The global paper cup sleeve market stands at a critical inflection point as 2026 begins. Between 2020 and 2025, the total addressable market expanded from approximately USD 485.2 million to a reaffirmed USD 642.5 million, reflecting a compound growth trajectory that underscores durable end-market demand, shifting consumer packaging expectations, and tightening operational efficiency requirements across foodservice supply chains. Looking ahead to the 2026 to 2032 forecast horizon, the market is projected to reach USD 916.19 million, guided by a five-year CAGR of 5.19 percent. These are not abstract statistics. They represent a decision architecture for procurement leaders, sustainability officers, product developers, and competitive strategists who must allocate capital, design supply resilience, and position portfolios against evolving regulation, material economics, and channel fragmentation. This article outlines the strategic logic embedded in our latest Worldwide Paper Cup Sleeve Market study and explains why the full report is essential reading for companies planning through the remainder of the decade.
At its core, this market is no longer a commodity wrap-around. It is a functional interface between thermal performance, brand expression, material compliance, and consumer experience. Sleeve specifications now influence beverage handling safety, perceived quality, cup compatibility, and downstream recyclability narratives. As chains scale operations and independent cafes defend differentiation, packaging decisions that once lived in the background now sit directly in the path of cost management, ESG reporting, and customer retention. Decision-makers therefore need more than directional market color. They need a structured map of how demand is forming, where margins concentrate, which capabilities command pricing power, and how regulatory momentum will reshape sourcing and design choices in each major geography.
Macro Trajectory and Decision Relevance
The trajectory from 2020 through 2025 shows a market that has repeatedly absorbed macroeconomic variance and still advanced. After a 2020 baseline of USD 485.2 million, the market moved to USD 531.1 million in 2021, USD 538.75 million in 2022, USD 579.77 million in 2023, USD 593.08 million in 2024, and USD 642.5 million in 2025. That progression indicates sustained absorption of sleeve volume across both high-frequency beverage channels and broader institutional deployment, even as inflation, freight volatility, and input-cost swings challenged margin discipline. The forecast path reinforces the same structural signal: from USD 677.12 million in 2026 to USD 743.97 million in 2027, USD 790.85 million in 2028, USD 805.91 million in 2029, USD 817.98 million in 2030, USD 885.76 million in 2031, and USD 916.19 million in 2032. The consistency of this expansion curve is strategically important because it tells executives that volume growth is not a one-time reopening artifact or a temporary consumer fad. It reflects a more persistent alignment of hot-beverage consumption patterns, on-the-go service models, and packaging decisions that prioritize insulation, handling comfort, and branding real estate.
Worldwide Paper Cup Sleeve Market
For 2026 planning, this trajectory matters in three practical ways. First, it sets a realistic envelope for capacity investment and working-capital planning, helping leaders avoid overbuilding or undercommitting against a market that is expanding, but not exploding. Second, it establishes a reference frame for performance benchmarking, enabling companies to ask whether their own growth rate, margin profile, and share movement are consistent with the broader market’s direction or whether they are gaining or losing relative ground. Third, it frames the timescale over which product strategy, supplier consolidation, and compliance readiness will mature. A 5.19 percent CAGR may appear moderate in isolation, yet it compounds into meaningful share shifts over multi-year horizons, particularly when paired with regulatory deadlines, material-price cycles, and retailer-driven specification changes. Companies that treat the forecast as an operational baseline rather than a marketing statistic will be better positioned to time product launches, renegotiate supply terms, and prepare for evolving customer requirements.
From Aggregate Growth to Operational Insight: What the Report Delivers
Aggregate figures provide direction, but durable strategy is built on segment logic, competitive posture, and the operational levers that convert demand into margin. Our study is structured to translate market movement into decision-grade intelligence across the dimensions that actually shape commercial outcomes. The report examines material architecture and design trade-offs, including the thermal, structural, and printability implications of corrugated paperboard, kraft paper, and smooth or embossed paper formats. These choices influence insulation performance, stacking behavior, machine runnability, label compatibility, and consumer tactile perception, and they also interact with recycling and composting narratives in ways that increasingly affect customer acceptance and compliance exposure. The analysis addresses application deployment across Coffee Shops and Cafes, Quick Service Restaurants, and Commercial and Institutional channels, with attention to volume concentration, specification sensitivity, purchasing cycles, and the differing ways each channel balances cost pressure against branding and functional performance. Regional deployment is mapped in a manner that helps executives understand where demand intensity, supply localization, and regulatory exposure converge, without reducing regional complexity to static percentage snapshots that obscure change dynamics.
Beyond segmentation, the report provides practical frameworks for sourcing strategy, cost volatility management, and channel-specific value proposition design. It assesses how manufacturers and converters are aligning product portfolios with sustainable fiber-based materials, recycled-content options, and certification positioning, while also evaluating where customization, print capability, and thermal engineering become sources of differentiation rather than table stakes. The study further incorporates recent market activity that signals where investment and partnership momentum is forming, including product launches that extend compostable and plant-based solutions, collaborative arrangements linking insulated packaging with enhanced thermal performance and recyclability, and closed-loop recycling initiatives tied to municipal and circular-economy objectives. These developments are not treated as isolated press items. They are read as indicators of how competitors are constructing future relevance and where buyers should expect specification pressure, volume reallocation, and compliance-linked purchasing criteria to intensify.
Competitive Posture and Strategic Positioning
The competitive landscape is shaped by a diverse set of participants, each approaching the sleeve market through a different combination of regional reach, product technology, sustainability positioning, and customer intimacy. Huhtamaki Oyj operates from Espoo, Finland, with insulated paper cup sleeves integrated into a global foodservice packaging portfolio that emphasizes recycled content and hot-beverage insulation. Dart Container Corporation, based in Mason, Michigan, focuses on paper and insulated sleeves for hot beverages in foodservice and quick-service contexts, building on thermal protection solutions tailored to high-throughput beverage service. Graphic Packaging International, headquartered in Atlanta, Georgia, manufactures paper-based packaging solutions that include cup sleeves, with a strong emphasis on sustainable fiber-based materials and conversion capability. Pactiv Evergreen Inc., located in Lake Forest, Illinois, supplies paper cup sleeves and related foodservice disposables, including products with sustainability attributes designed for hot drink applications. Benders Limited, based in Wellingborough, UK, produces paper cups and complementary sleeves using sustainably sourced materials and FSC certifications, giving it a credentials-led position in segments where environmental assurance influences procurement decisions.
The competitive field also includes firms with clearer emphasis on customization, branding, and export-oriented scale. Zhejiang Pando EP Technology Co., Ltd., in Zhejiang, China, specializes in wholesale paper sleeves for coffee cups, including kraft and custom options, with distribution reaching Europe, the US, and other markets. Suzhou Accum Packaging Co., Ltd., in Suzhou, China, manufactures custom paper cup sleeves with design flexibility for food and beverage packaging, supported by FSC and ISO certifications. HotShot Sleeves, based in the USA, concentrates on custom printed paper coffee sleeves and related beverage packaging for branding in the US market. Ibex Packaging, also US-based, supplies custom printed paper cup sleeves tailored for branding and insulation needs. LBP Manufacturing LLC, operating in the USA, offers insulated paper cup sleeves designed for hot beverage thermal protection in foodservice. Together, these players illustrate a market in which insulation performance, print personalization, certification credibility, and regional service capability all compete for relevance against price and scale.
The market structure itself reinforces the importance of careful positioning. With CR3 at 18.5 percent and CR5 at 24.2 percent, the industry is not dominated by a small number of universal incumbents. Instead, it rewards capability depth, customer-specific responsiveness, and supply reliability in ways that can enable focused players to hold defensible positions even as larger portfolios expand across adjacent categories. This fragmentation matters for strategy because it means share dynamics can move through product differentiation, customer lock-in, regional fulfillment quality, and compliance-driven specification changes rather than through sheer scale alone. The report uses this competitive context to help leaders identify where consolidation pressure is likely to build, where customer bargaining power may intensify, and where specialized positioning can be defended through technology, service, or sustainability credentials.
Regulatory Momentum, Material Economics, and Operating Conditions
Strategy in this market cannot be separated from the operating environment. Two structural forces are reshaping how paper cup sleeves are specified, sourced, and evaluated: regulation and raw-material economics. On the regulatory side, the EU Packaging and Packaging Waste Regulation entered into force in February 2025 and applies from August 2026, mandating extended producer responsibility schemes with modulated fees based on recyclability for packaging that includes paper products. In parallel, as of 2025, seven US states, including California, Colorado, Maine, Maryland, Minnesota, Oregon, and Washington, have enacted packaging EPR laws covering paper products and foodservice ware, with reporting and fee obligations now in play. California SB 54 further requires 100 percent of single-use packaging and food service ware to be recyclable or compostable by 2032, a requirement that directly affects sleeve design choices, material selection, and end-of-life narratives for hot-beverage packaging. These developments are not remote risks. They are becoming purchase criteria, cost drivers, and design constraints that influence supplier selection and product architecture well before the compliance horizon closes.
Worldwide Insulated Cup Sleeves Market
Material economics add a second layer of strategic sensitivity. Paper cup sleeves primarily use kraft paper or corrugated paperboard as the raw material for thermal insulation and structural integrity, so input cost behavior feeds directly into margin performance and pricing strategy. In this context, kraft paper prices in the first quarter of 2026 varied regionally, with China at USD 891 per metric ton and France at USD 1462 per metric ton. That range is more than a data point. It signals that sourcing geography, logistics structure, hedging behavior, and specification flexibility can determine whether a company absorbs cost pressure or passes it through. It also reinforces the value of understanding which material formats and design specifications provide the best combination of performance, compliance readiness, and cost control in each operating environment. The report builds these dynamics into its analysis so that readers can evaluate not just where the market is going, but how operating conditions will shape profitability along the way.
Why the Full Study Is Essential for 2026 Decision-Making
The worldwide paper cup sleeve market is expanding on a credible, multi-year curve, but growth alone does not create strategy. Competitive advantage will come from the ability to interpret segmentation shifts, anticipate specification pressure, manage material volatility, and align product portfolios with regulatory and customer expectations before those expectations harden into procurement mandates. The full study gives decision-makers the detailed segmentation logic, competitive context, development signals, and operating-condition analysis needed to turn that opportunity into action. It is designed for teams that must answer practical questions about where to invest, how to position for compliance, which customer segments carry the best value-and-risk balance, and how to build sourcing and product strategies that hold up under changing regional conditions. To access the complete segmentation analysis, forecast architecture, competitive profiles, and decision frameworks, visit the source page for the Worldwide Paper Cup Sleeve Market research and obtain the full intelligence set built for 2026 planning and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Paper Cup Sleeve Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Global Education Computing Devices To Hit $57.9B By 2032 With 14.5% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Digital Classroom: Inside the Worldwide Education Computing Devices Market
The global education technology landscape is undergoing a profound transformation. As schools and universities pivot from emergency remote learning to sustained, technology-enabled pedagogical models, the procurement of computing devices has become a cornerstone of institutional strategy. For executives, procurement leaders, and investors, understanding the trajectory of this market is no longer optional. It is a prerequisite for capital allocation, product roadmap planning, and supply chain resilience. Our recently published Worldwide Education Computing Devices Market research study delivers a comprehensive, data-rich blueprint of this evolving sector. This article outlines the strategic value of the report, previews its analytical architecture, and demonstrates how decision-makers can leverage its findings to navigate the 2026–2032 forecast horizon with confidence.
A Market Poised for Sustained Expansion
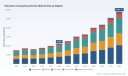
The education computing devices sector has demonstrated remarkable resilience and growth momentum over the past half-decade. Historical revenue data from 2020 through 2025 reveals a sector that recovered swiftly from early-pandemic supply chain disruptions and then accelerated into a phase of structural expansion. In 2020, global market revenue stood at approximately 15.2 billion USD. By 2025, that figure had climbed to 22.45 billion USD, reflecting a compound trajectory driven by renewed institutional budgets, refreshed device fleets, and the normalization of digital-first learning environments.
Looking forward, our forecast model projects that the market will reach roughly 25.25 billion USD in 2026 and continue its upward climb through 2032, when total revenue is expected to surpass 57.9 billion USD. This growth path translates to a forecast-period compound annual growth rate of 14.5 percent. Such a rate places education computing devices among the more dynamic hardware verticals in the broader technology ecosystem. The acceleration is not merely a function of post-pandemic catch-up; it is rooted in durable shifts in curriculum design, administrative digitization, and the integration of artificial intelligence into classroom workflows.
It is important to emphasize that these headline figures represent the aggregated global total. The underlying distribution across geographies, device categories, and end-user segments contains significant variation that can materially impact regional strategy, pricing architecture, and inventory planning. Our full report dissects these layers in granular detail, providing the precision required for localized execution while preserving the macro perspective necessary for board-level strategic planning.
What the Report Delivers: A Framework for Action
A market research publication is only as valuable as its actionable granularity. Our study is engineered to serve as an operational reference rather than a high-level overview. The report is structured around several interlocking analytical modules, each designed to answer specific strategic questions facing education technology stakeholders.
- Historical Reconstruction and Baseline Calibration: We reconstruct revenue performance from 2020 through 2025 across multiple dimensions, establishing a verified baseline that accounts for procurement cycles, policy shifts, and supply-side constraints. This historical lens enables clients to benchmark their own performance against market-wide trends and identify periods of outperformance or underperformance.
- Forward Forecast with Scenario Sensitivity: The 2026–2032 projection framework incorporates multiple growth drivers, including device refresh rates, curriculum modernization mandates, and emerging AI-enabled classroom requirements. The forecast is presented with clear methodological transparency so that readers can test assumptions against their own internal models.
- Device-Type Architecture: The study segments the market across laptops, Chromebooks, tablets, and desktop/hybrid units. Each category is evaluated in terms of adoption momentum, total cost of ownership considerations, and suitability for distinct instructional models. The analysis highlights how procurement preferences are evolving as schools balance performance, manageability, and budget constraints.
- End-User Segmentation: K-12 education and higher education represent distinct buying cultures, funding mechanisms, and deployment scales. Our report maps the demand dynamics within each segment, revealing where volume concentration lies and which institutional profiles are driving incremental growth.
- Competitive Positioning and Mobility Assessment: We profile the major participants shaping the market, examining product strategies, ecosystem leverage, and recent commercial moves. The analysis goes beyond static company descriptions to evaluate how firms are positioning themselves for the next wave of education-focused hardware and software integration.
- Regulatory and Infrastructure Context: Technology procurement does not occur in a vacuum. The report integrates relevant policy developments, connectivity considerations, and infrastructure cost signals that influence device accessibility, total deployment cost, and long-term sustainability for educational institutions.
Competitive Landscape: Who Shapes the Market and How
The education computing devices market is characterized by a concentrated yet dynamic competitive field. Our concentration analysis indicates that the top three firms collectively account for approximately 42.15 percent of total market revenue, while the top five firms represent roughly 64.8 percent. This level of concentration suggests that scale, brand trust, and institutional relationship depth remain powerful differentiators. At the same time, the presence of multiple well-capitalized players competing across overlapping product categories ensures continuous innovation in durability, manageability, and price-to-performance ratios.
Several corporations stand out for their dedicated education-focused portfolios and deployment track records. HP Inc. has built a strong reputation for durable, education-specific Chromebooks and laptops that are widely deployed in K-12 1:1 programs globally. Their education-optimized models emphasize long battery life and centralized manageability, attributes that align closely with the operational realities of large school districts. Dell Technologies Inc. similarly offers Chromebooks and laptops tailored for education, with a pronounced focus on durability, serviceability, and integration for school deployments. Dell's footprint includes substantial institutional contracts, such as its involvement in large-scale public school procurement initiatives.
Lenovo Group Limited supplies education Chromebooks and laptops designed for K-12 durability, affordability, and increasingly AI-enhanced features. Their recent product cadence reflects a deliberate push toward connectivity improvements and classroom-ready form factors. Acer Inc. delivers budget-friendly Chromebooks and education laptops optimized for student use, with long battery life and touchscreen options that appeal to cost-conscious procurement offices. ASUTeK Computer Inc. (ASUS) produces education-focused Chromebooks and Windows laptops that emphasize inclusivity, rugged design for students with special educational needs, and AI features, as evidenced by their recent education portfolio unveilings.
Beyond the traditional hardware manufacturers, platform and ecosystem players exert considerable influence. Apple Inc. provides iPads, MacBooks, and ecosystem tools for education, supported by initiatives that include partnerships for coding and robotics in schools and managed device deployment capabilities. Samsung Electronics Co., Ltd. offers Galaxy Chromebooks, tablets, and interactive displays for classrooms, including premium AMOLED models with AI integration tailored for education. Google LLC, through its ChromeOS and Chromebook ecosystem, provides management tools, AI features, and devices optimized for K-12 education, with a substantial installed base already deployed globally.
Recent commercial activity underscores the pace of evolution. In early 2026, ASUS unveiled an expanded education portfolio at a major industry event, introducing Windows laptops, Chromebook series, detachable models, and AI-enhanced devices focused on durability, accessibility, zero-touch enrollment, and efficient deployment. Around the same period, Lenovo launched new Chromebook series featuring advanced connectivity standards, targeting education durability and performance. Separately, a major municipal procurement initiative announced the distribution of hundreds of thousands of LTE/5G-connected Chromebooks to K-12 public school students across a large network of schools, signaling the continued importance of cellular connectivity in closing digital access gaps. These moves illustrate how product launches, connectivity integration, and large-scale deployment contracts are reshaping the competitive playing field.
Market Dynamics: Policy, Infrastructure, and the Connectivity Imperative
Hardware adoption in education is intimately tied to the policy and infrastructure environment. Several developments in recent months carry direct implications for device procurement strategies and long-term market trajectories.
Worldwide Education Computing Devices Market
First, the regulatory landscape around broadband and internet access continues to evolve. A recent appellate court decision struck down a prior federal net neutrality order, reclassifying broadband as an information service and shifting potential regulatory oversight to state-level bodies or legislative action. For education stakeholders, this development introduces uncertainty around equitable access to digital learning content. However, it also intersects with a broader policy conversation: public interest exceptions to net neutrality rules in various jurisdictions allow zero-rating or prioritized access for educational content to support digital learning initiatives. Institutions and vendors alike must monitor how these exceptions are applied, as they can influence device utility, content delivery costs, and the perceived value of connectivity-enabled hardware.
Second, infrastructure cost dynamics are entering the strategic calculus. Major technology firms have recently committed to covering the costs of new power generation and grid upgrades for data centers to prevent increases in residential electricity prices. While this pledge is primarily directed at data center operations, it signals a broader recognition that the digital infrastructure underpinning cloud-based education tools, device management platforms, and AI features depends on reliable and affordable power. Over time, these infrastructure commitments may help stabilize the operational environment for cloud-reliant education deployments, though regional variability in electricity pricing and grid capacity will remain relevant for large-scale device rollouts.
Third, the connectivity gap remains a persistent strategic concern. The distribution of LTE/5G-connected devices to students in large public school systems reflects a policy-driven effort to ensure that learning can continue regardless of home broadband availability. For vendors and institutional buyers, this trend reinforces the importance of cellular-equipped devices, subscription management models, and partnership structures that bundle hardware with connectivity services. It also highlights the need for procurement frameworks that account for total cost of ownership over multiple years, rather than focusing solely on upfront hardware expenditure.
Strategic Implications for 2026 Decision-Making
The convergence of strong market growth, concentrated competition, and evolving policy and infrastructure conditions creates both opportunity and complexity. Leaders who engage with this market in 2026 must navigate several interrelated strategic questions. How should device portfolios be balanced across categories to match instructional needs and budget realities? Where do regional demand patterns justify localized supply chain or distribution investments? How can procurement teams evaluate competing device and ecosystem offerings without losing sight of long-term manageability and total cost of ownership? And how should organizations position themselves for the integration of AI features, connectivity upgrades, and accessibility requirements into next-generation education hardware?
Our report is designed to equip decision-makers with the evidence base required to answer these questions. By combining macro-level revenue trajectories with category-level insight, competitive profiling, and contextual analysis of regulatory and infrastructure developments, the study provides a multi-layered view of the market. This allows clients to move beyond generic industry narratives and develop strategies that are calibrated to their specific operating context, risk tolerance, and growth ambitions.
Access the Full Intelligence
The Worldwide Education Computing Devices Market research study offers a complete, methodologically rigorous portrait of a sector that is expanding at a compelling pace and being reshaped by technology, policy, and institutional demand. The summary figures and strategic themes outlined here provide a preview of the report's scope and analytical depth, but they are only a starting point. The full study contains detailed segmentation breakdowns, regional demand analysis, category-level revenue trajectories, competitive benchmarking, and forward-looking scenario discussions that are essential for precise planning.
AI Learning Devices for Kids Market
For executives, procurement leaders, investors, and strategy teams seeking to make informed decisions in 2026 and beyond, the complete report delivers the granularity and context needed to translate market intelligence into action. We invite you to access the full study to explore the data, models, and insights that will support your next strategic move in the education computing devices market.
For detailed analysis of this topic, please visit the official page: Worldwide Education Computing Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Managed Security Services Market to Hit $86.78 Billion by 2032, Growing at 11.5% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence for 2026: Navigating the Managed Security Services System Landscape
The enterprise security paradigm has fundamentally shifted. In an environment where threat vectors evolve faster than internal teams can patch, the Managed Security Services System market has emerged as a critical infrastructure layer for organizations of every scale. Our latest market research report provides a comprehensive, data-grounded evaluation of this sector, designed specifically to equip executive decision-makers with the situational awareness required for 2026 strategy formulation and capital allocation.
Drawing on historical performance spanning 2020 through 2025 and projecting through 2032, this analysis maps a market trajectory that has demonstrated remarkable resilience and compounding growth. The sector expanded from approximately 23.5 billion USD in 2020 to 40.5 billion USD by the base year of 2025, with forward modeling indicating a climb toward 44.27 billion USD in 2026 and a projected 86.78 billion USD by 2032. These figures reflect a compound annual growth rate of 11.5 percent throughout the forecast period, signaling sustained demand that outpaces broader IT services growth. For procurement leaders, CFOs, and security architects, this trajectory is not merely a number; it is a structural signal that managed security is transitioning from an optional outsourcing convenience to a non-negotiable operational requirement.
This report functions as a strategic compass. Rather than offering superficial vendor comparisons, it delivers operational frameworks, competitive mapping, and regulatory context that enable organizations to align their security outsourcing decisions with broader business objectives. The insights enclosed are structured to answer the questions that keep executives awake at night: Which service models will deliver sustainable ROI? How is the competitive landscape consolidating, and what does that mean for contractual leverage? And where should capital be deployed in 2026 to future-proof security operations without overcommitting to legacy architectures?
Macro Market Dynamics Shaping 2026 Decision-Making
The growth narrative of the Managed Security Services System market is being rewritten by intersecting technological, regulatory, and operational forces. At the center of these dynamics is the overwhelming security talent shortage that continues to widen globally. Organizations of every size are discovering that building and sustaining an in-house security operations center is increasingly cost-prohibitive, politically difficult within corporate budgets, and operationally fragile when key personnel depart. Managed service providers fill this gap by delivering continuous monitoring, threat hunting, incident response, and compliance oversight at a scale that internal teams simply cannot match.
Simultaneously, the regulatory environment has intensified dramatically. In early 2026, more than 300 data center-related bills were introduced across 30 US states, addressing energy costs, grid reliability, and special tariffs for large energy consumers such as data centers supporting security services. This regulatory wave directly influences the operating cost structures of providers delivering always-on monitoring and cloud-native security platforms. Complementing this state-level activity, the US White House Ratepayer Protection Pledge now requires hyperscalers and AI or data center operators to cover the full costs of energy generation and infrastructure, ensuring that household ratepayers are not burdened by the power demands of digital infrastructure expansion. For organizations evaluating managed security contracts, these policies introduce new considerations around where services are hosted, how data sovereignty requirements intersect with energy cost pass-throughs, and which providers have already optimized their infrastructure for regulatory resilience.
Cross-border data governance continues to evolve as another defining constraint. The United States has increasingly challenged foreign data sovereignty and localization requirements in recent trade reports, aiming to support cross-border managed security and cloud services. At the same time, the US Department of Justice Bulk Data Rule, effective from 2025, mandates stringent cybersecurity controls for certain bulk personal data transactions involving foreign parties. This creates a complex compliance matrix that managed security partners must navigate, and it elevates the strategic value of providers who can attest to jurisdictional awareness, audit readiness, and data handling architecture that satisfies both domestic and international regulators.
These dynamics are not isolated observations. They are embedded throughout the report's analysis of market concentration, service adoption patterns, and provider positioning, giving readers a realistic foundation for scenario planning rather than optimistic projections untethered from operational reality.
Competitive Ecosystem and the Providers Defining the Next Phase
The competitive landscape of managed security services is characterized by a blend of established technology conglomerates, specialized pure-play MSSPs, and emerging platform-native operators. Market concentration data indicates that the top three providers collectively command approximately 22.4 percent of total revenue, while the top five reach roughly 34.1 percent. This moderate concentration suggests an environment where scale players exert influence but significant differentiation and regional specialization remain possible, preventing complete market consolidation.
Managed Security Services System Market
Several organizations define the strategic contours of this space. IBM Security provides 24/7 Managed Security Services encompassing monitoring, management, and response to advanced threats, risks, and compliance needs across hybrid cloud environments, positioning itself as a provider capable of operating at enterprise complexity. Verizon leverages its global network infrastructure to deliver Managed Security Services that span threat detection, mitigation including DDoS, SASE capabilities, and incident response for enterprises and government clients, using network scale as a core competitive advantage. LevelBlue, formed from the combination of AT&T Cybersecurity and Trustwave, operates as a pure-play MSSP delivering 24/7 MDR, managed security, offensive security, and FedRAMP-authorized services, an architecture that appeals particularly to regulated and public sector buyers. Tata Communications delivers global Managed Security Services with a focus on network-integrated security monitoring and threat management, bringing international connectivity expertise into the security operations layer.
On the detection and response side, Secureworks provides managed threat detection and response services through its Taegis XDR platform, Arctic Wolf offers a Concierge Security team for 24x7 managed detection and response across endpoints, networks, and cloud, and eSentire delivers MDR with 20/7 expert-led security operations. Each of these organizations brings a distinct operational philosophy—platform-led, concierge-led, or network-integrated—creating meaningful differentiation for buyers with varied risk appetites and internal maturity levels.
Recent developments in 2025 and early 2026 illustrate how rapidly this competitive field is evolving. NWN launched an AI-enabled managed security operations suite in April 2026, incorporating MDR, offensive security services, ransomware protection, and vCISO services alongside new platform integrations, signaling a broad consolidation of advisory and defensive capabilities into unified operations platforms. Beyond was named the 2026 Google Cloud Security Managed Security Service Provider for EMEA, recognized for agentic SOC capabilities, underscoring the growing relevance of automated and semi-autonomous response architectures in regional markets. LevelBlue was named a Representative Vendor in the 2026 Gartner Market Guide for Outsourced Managed Security Services, reinforcing the credibility of pure-play MSSPs within analyst-recognized frameworks. Palo Alto Networks introduced Next-Generation Trust Security with certificate lifecycle automation designed to support managed security resilience, demonstrating how traditional platform vendors continue to reshape the managed services ecosystem through infrastructure trust mechanisms.
The report maps these players and developments not as a static vendor directory but as a living competitive topology. It examines how service bundling, platform automation, and partnership ecosystems are reshaping procurement leverage, contract flexibility, and long-term vendor stickiness. This framing enables organizations to evaluate providers against operational fit rather than marketing claims.
Report Architecture and Operational Content
The research has been constructed to serve as a working reference rather than a high-level summary. Content is structured across multiple analytical dimensions that directly support strategy, procurement, and risk management functions.
Service Model and Solution Coverage
The analysis examines the dominant managed security service categories shaping buyer demand. Managed Firewall and Network Security, Managed IDS and IPS, Managed Threat Intelligence and Response, and Vulnerability and Compliance Management each receive dedicated evaluation regarding adoption momentum, integration complexity, and the operational outcomes they deliver. The report contextualizes how these service lines intersect with broader architectures such as SASE, XDR, and agentic SOC models, enabling readers to assess which capabilities align with their current maturity and which gaps require staged investment.
Organization Size and Procurement Dynamics
The market serves both small and mid-sized enterprises and large enterprises, but the purchasing behavior, risk tolerance, and service expectations differ substantially between these cohorts. The report disentangles these patterns, exploring how organizational scale influences contract structures, service bundling, internal resource supplementation strategies, and the financial justification for outsourcing versus building internal capabilities. This provides procurement leaders with a clearer lens for segmenting their organization's needs and matching them to service arrangements that reflect actual operational reality.
Regional Context and Cross-Border Considerations
Regional analysis is presented with attention to the operational and regulatory forces that shape deployment decisions, rather than as isolated market share tables. The interplay between energy policy, data sovereignty, localization requirements, and cross-border service delivery is examined in a way that helps organizations anticipate friction points in multi-region security operations. This regional framing is especially relevant for multinational enterprises and for providers expanding their managed security footprint across jurisdictions with diverging compliance expectations.
Competitive Benchmarking and Vendor Strategy
Beyond company profiles, the report delivers a structured competitive assessment that evaluates provider positioning, service differentiation, partnership ecosystems, and recent strategic moves. It explores how AI-enabled operations, certificate lifecycle automation, agentic SOC capabilities, and offensive security service integration are reshaping vendor offerings and buyer expectations. This competitive mapping is intended to support vendor evaluation, negotiation strategy, and long-term partnership selection, giving readers a defensible basis for decision-making in a crowded and fast-moving market.
Regulatory and Cost-Structure Implications
Regulatory developments are not treated as footnotes but as structural drivers that alter provider economics and buyer risk exposure. The analysis integrates the latest policy context surrounding data center energy regulation, hyperscaler cost obligations, data sovereignty challenges, and bulk data transaction controls to illustrate how these forces influence service pricing, hosting architecture, compliance overhead, and contract terms. By connecting regulatory dynamics to operational consequences, the report equips leaders to incorporate policy risk into their security outsourcing calculus.
Scenario Planning and 2026–2032 Outlook
The forecast period is treated as a range of plausible trajectories rather than a single deterministic line. Forward modeling incorporates historical performance from 2020 to 2025 and projects growth through 2032, enabling organizations to stress-test investment scenarios, capacity planning, and service evolution roadmaps. This scenario-oriented outlook supports budgeting discipline and strategic flexibility, allowing leaders to align security outsourcing commitments with the pace of organizational transformation and threat environment evolution.
Strategic Imperatives for Enterprise Decision-Makers
The core message of this research is that managed security services are entering a phase of maturation where differentiation is driven less by whether organizations outsource security and more by how precisely they select, govern, and integrate managed capabilities into their broader risk and operations strategy. The data confirms sustained market expansion, but the strategic value for 2026 lies in understanding which service models, provider archetypes, and contractual structures will deliver durable value as the competitive field consolidates and regulatory pressure intensifies.
Leaders evaluating this market in 2026 should treat the following as guiding priorities: aligning managed service scope with actual internal capability gaps, scrutinizing provider architectures for data handling and jurisdictional compliance, evaluating the operational maturity of provider SOC and response functions rather than relying on portfolio breadth alone, and anticipating cost-structure shifts driven by energy policy and infrastructure obligations. The organizations that approach these decisions with disciplined analysis will be better positioned to convert managed security from a compliance expense into a strategic operational advantage.
Manned Security Services Market
Complete access to the full dataset, detailed segmentation analysis, vendor benchmarking frameworks, and scenario models is available through the full report. The executive summary provided here is intended to establish the analytical foundation and demonstrate the depth of coverage, while encouraging decision-makers to consult the complete intelligence package for the granular data required to translate strategic direction into actionable procurement and investment plans.
For detailed analysis of this topic, please visit the official page: Managed Security Services System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Automotive Water Separation System Market to Reach $2,059.53M by 2032 at 5.02% CAGR
By pmarketresearch, 2026-09-16
Navigating the Automotive Water Separation System Market: Strategic Imperatives for 2026 and Beyond
As global automotive engineering pivots toward higher efficiency, stricter emissions compliance, and increasingly complex fuel architectures, the water separation system has evolved from a passive maintenance component to a mission-critical engineering subsystem. Water contamination in diesel and heavy-duty fuel streams accelerates injector wear, triggers microbial growth in storage infrastructure, and compromises combustion stability. With regulatory frameworks tightening and powertrain architectures evolving, the strategic importance of reliable water separation has never been more pronounced. This article outlines the macro trajectory of the market, the forces reshaping competitive dynamics, and how PW Consulting’s latest Worldwide Automotive Water Separation System Market study equips leadership teams with the intelligence required to navigate 2026 decision-making with precision.
Market Trajectory: A Decade of Structured Growth and Strategic Inflection
The global automotive water separation system market has demonstrated consistent expansion over the past half-decade, driven by replacement demand, emissions-driven design mandates, and the continuous modernization of commercial fleets. Historical revenue evaluations from 2020 through the base year of 2025 reveal a disciplined upward arc, with valuations moving from the 1,145 million USD range to approximately 1,462 million USD in the most recent assessment period. This progression reflects not only incremental volume growth but also the structural premiumization of filtration architectures as OEMs and aftermarket channels prioritize higher separation efficiency over commoditized cost profiles.
Looking forward, the forecast window spanning 2026 through 2032 projects a sustained compound annual growth rate of roughly 5.02 percent. Under this trajectory, the market is expected to cross the 1,560 million USD threshold in 2026 before advancing toward the 2,060 million USD vicinity by the terminal forecast year. Such a growth cadence signals a mature but still expanding addressable space, where incremental gains will emerge from technology upgrades, regional fleet turnover cycles, and the integration of smarter sensing and monitoring capabilities into traditional mechanical separation assemblies. For strategic planners, this macro arc provides a foundational baseline: growth is real and measurable, but its distribution across vehicle classes, geographic corridors, and component categories demands granular, scenario-based intelligence rather than blanket assumptions.
While the aggregate numbers convey directional confidence, the real strategic value lies beneath the surface. Companies that attempt to allocate capital, capacity, or supplier negotiations based solely on headline valuations risk missing the uneven pacing of regional adoption, the divergent replacement cycles of heavy commercial versus passenger platforms, and the shifting cost structures of specialty media and electronic subcomponents. The full report deconstructs these layers without relying on simplified averages, enabling executives to align procurement, R&D, and go-to-market strategies with the specific demand pockets that will actually drive margin in the coming years.
Competitive Landscape: Ten Navigators Shaping the Filtration Ecosystem
The industry is anchored by a concentrated group of technically rooted manufacturers that have built decades of material science, fluid dynamics expertise, and direct OEM relationships. A handful of global leaders command meaningful share, while a broader field of specialized suppliers competes through niche engineering advantages, regional service networks, and application-specific validation credentials. Understanding who holds leverage where, and why, is essential for anyone evaluating partnership structures, substitution risks, or supply chain exposure.
American-headquartered firms continue to set the pace in heavy-duty and off-road applications. Donaldson Company has reinforced its position with media innovations tailored to low-sulfur diesel environments, most recently advancing its filtration media portfolio to improve separation efficiency under tighter fuel specifications. Parker Hannifin, operating through its Racor division, has expanded its footprint by securing supplier nominations for next-generation truck platforms, embedding its Aquabloc media technology into integrated fuel management architectures. Meanwhile, Cummins Inc., through its Fleetguard division, continues to validate its separation hardware against stringent engine-level cleanliness targets, demonstrating the direct linkage between water management and downstream emissions and performance commitments.
On the European side, engineering heritage and OEM integration depth define the competitive rhythm. Mann+Hummel and Mahle both deliver multifunction filtering architectures that combine water extraction with particulate management, supporting the gradual convergence of fuel preparation and emissions compliance. Hengst SE focuses heavily on heavy-duty diesel platforms, while Sogefi Group leverages its modular system approach to serve global OEM supply chains with standardized yet adaptable separation modules. Separ Sweden AB brings a distinct technical angle through swirl-based separation principles, offering an alternative mechanical pathway for diesel fuel conditioning in demanding applications.
Worldwide Automotive Water Separation System Market
The North American aftermarket and commercial truck ecosystem also remains highly active. Davco Technology, operating under the Eaton umbrella, continues to supply separation and filtration assemblies engineered for medium- and heavy-duty trucks, while Baldwin Filters maintains a strong pedigree in diesel-powered commercial and agricultural platforms through proven housing and bowl configurations. Together, these players illustrate a market where technical differentiation, validation credibility, and tier-one integration relationships matter far more than generic scale alone.
Recent activity underscores that this is not a static field. Product launches, joint development agreements, and validation milestones have accelerated over the past year, signaling that incumbents are actively future-proofing their portfolios against evolving fuel standards and engine cleanliness requirements. Executives evaluating vendor stability, substitution risk, or co-development opportunities need a clear map of who is investing where, which platforms are being targeted, and how recent validation events shift bargaining power in negotiations. The complete competitive assessment in the full study details these strategic alignments and the implied consequences for sourcing, partnership design, and market entry planning.
Forces Reshaping the Market: Regulation, Materials, and Technical Bottlenecks
Market dynamics in this segment are being shaped by a convergence of regulatory mandates, material economics, and technical ceilings. European fuel specifications have progressively tightened allowable water content in diesel streams, compelling OEMs and fleet operators to invest in more effective separation hardware to maintain compliance and protect downstream components. In parallel, nonroad engine standards in key jurisdictions have elevated minimum water removal efficiency expectations, effectively forcing a functional baseline above which only more advanced architectures can reliably perform.
Material-side pressures are equally important. The pricing environment for specialty media inputs, particularly glass microfiber variants used in high-efficiency coalescing elements, has experienced volatility due to supply chain constraints in borosilicate production. Such fluctuations directly affect cost planning for manufacturers and complicate margin forecasting for procurement teams that rely on stable input assumptions. At the same time, certain coalescing polymer membrane approaches are encountering practical limitations when tasked with achieving extremely low residual water thresholds required for emerging compliance frameworks. This technical ceiling is encouraging a broader exploration of hybrid designs, enhanced pre-separation geometries, and sensor-assisted monitoring that can validate performance without relying solely on incremental media upgrades.
Another important nuance is the divergence between fuel types. In gasoline direct injection applications, the inherent solubility characteristics of modern petrol mean that water separation hardware is generally not a focal requirement, which concentrates commercial attention and engineering investment on diesel and heavy-duty domains. This structural difference matters for portfolio strategy: it means growth attention, validation spend, and supplier negotiations should be weighted toward the segments where water management remains a persistent operational and compliance priority.
The interplay of regulation, raw material economics, and technology maturity creates a landscape where static planning is quickly outdated. Companies must continuously assess how new fuel standards alter the minimum viable architecture, how media cost trends influence aftermarket pricing, and whether emerging separation approaches can credibly close the gap toward next-generation cleanliness thresholds. Our report maps these dynamics into actionable scenario considerations, helping leaders distinguish transient fluctuations from durable structural shifts.
From Intelligence to Execution: How the Study Supports 2026 Decisions
For strategy, procurement, product planning, and investor relations teams, the value of a market study lies not in confirming that growth exists, but in exposing the conditions under which growth translates into profitable opportunity. The PW Consulting Worldwide Automotive Water Separation System Market research is structured to support exactly that transition from awareness to execution. Rather than offering a single static snapshot, the analysis integrates historical baseline data, multi-year forward projections, component-level segmentation, vehicle-type differentiation, and regional demand contours into a decision-ready framework.
Oil Water Separator Market
Practically, this means the study is designed to help leadership teams answer questions that generic market narratives typically leave unresolved: which component categories are absorbing the greatest value migration as designs become more integrated; where replacement cycles and fleet turnover create more predictable demand rhythms; how OEM integration priorities differ from aftermarket replacement behavior; and where competitive intensity is likely to compress price expectations versus where technical barriers sustain healthier margins. The report also provides a structured view of concentration dynamics, helping readers gauge how much market leverage is concentrated among leading participants and where opportunities exist for specialized entrants or regional challengers.
Beyond segmentation, the study incorporates an operational lens on supplier behavior, validation activity, and recent portfolio developments. By connecting product announcements, engineering partnerships, and testing milestones to broader demand trends, the analysis helps executives interpret whether a competitor’s movement represents a genuine platform shift or a tactical positioning play. This is particularly valuable when negotiating with tier suppliers, evaluating joint development proposals, or deciding whether to commit internal R&D resources toward a specific separation technology pathway.
The report is also intended to support cross-functional alignment. Finance teams can use the projection architecture to ground revenue scenarios in a defensible macro baseline. Engineering and procurement can benchmark component-level demand against raw material exposure and design migration trends. Commercial teams can identify where regional demand intensity is likely to favor localized service and inventory positioning versus where centralized supply strategies remain appropriate. The overarching objective is to replace directional assumptions with a structured intelligence base that can be directly tied to capital allocation, sourcing strategy, and product roadmap decisions.
What the Full Study Unlocks
While this overview establishes the strategic context, the complete Worldwide Automotive Water Separation System Market report delivers the detailed architecture needed to operationalize these insights. It systematically addresses the structural composition of demand, the pacing of adoption across different platform categories, and the component-level dynamics that influence pricing, sourcing, and engineering priorities. It also lays out the competitive positioning logic that separates sustained market influence from short-term promotional activity, giving readers a clearer lens through which to interpret supplier claims and partnership opportunities.
For decision-makers preparing for 2026 and the subsequent forecast horizon, the difference between a useful market summary and an actionable intelligence product is granularity with purpose. The full study is built to provide exactly that: enough analytical depth to support scenario planning, supplier evaluation, and investment prioritization, while keeping the most decisive segmentation data and strategic readouts within the structured report environment. Readers ready to move from directional confidence to precise execution will find that the detailed breakdown of market structure, competitive behavior, and forward demand logic offers a more reliable basis for committing resources where they will matter most.
The automotive water separation system market is not simply expanding; it is being redefined by compliance pressure, material economics, and design integration. In that environment, the organizations that outperform will be those that can convert market intelligence into disciplined choices about where to supply, what to engineer, whom to partner with, and how to price against a changing technical baseline. The full study is designed to make that conversion faster, clearer, and more defensible.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Water Separation System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Automotive Engine Oil Additives Market Hits $18.02B in 2025, Forecasts 3.21% CAGR to 2032
By pmarketresearch, 2026-09-16
Navigating the Next Wave: Strategic Imperatives in the Global Automotive Engine Oil Additives Market (2026–2032)
As the automotive industry accelerates toward stricter emissions mandates, advanced powertrain architectures, and evolving performance standards, the engine oil additives sector stands at a critical inflection point. For executives, product developers, and market strategists operating within the lubricants value chain, understanding the trajectory of this market is no longer optional—it is a strategic necessity. Our latest Worldwide Automotive Engine Oil Additives Market research study delivers a comprehensive, forward-looking intelligence framework designed to equip decision-makers with the actionable insights required to navigate the 2026–2032 forecast period with precision.
The global market for automotive engine oil additives has demonstrated remarkable resilience and steady expansion over the past half-decade. Valued at approximately 15.2 billion USD in 2020, the sector has grown consistently to reach an estimated 18.02 billion USD by 2025. This upward trajectory is projected to continue, with the market expected to surpass 19.18 billion USD in 2026 and ultimately approach 22.47 billion USD by 2032. Driven by a compound annual growth rate (CAGR) of 3.21 percent across the forecast horizon, the industry reflects a mature yet innovation-led landscape where incremental gains in formulation efficiency, regulatory compliance, and regional demand shifts will dictate competitive advantage.
However, top-line growth figures only tell part of the story. The real strategic value of our report lies in its granular dissection of market architecture, competitive maneuvering, and the regulatory and macroeconomic forces that will reshape sourcing strategies, pricing architectures, and product development timelines. This article serves as a strategic preview of the full research publication, highlighting the analytical depth, operational frameworks, and competitive intelligence contained within—and explaining why institutional investors, OEM formulation teams, and additive suppliers must treat this study as an essential planning instrument for the next seven years.
Market Architecture and Segmentation Dynamics
The automotive engine oil additives landscape is inherently multi-dimensional, shaped by product chemistry, vehicle application profiles, and geographically dispersed demand centers. Our research systematically maps these intersecting layers to provide a clear view of where volume concentration exists and where emerging opportunities are materializing.
When analyzing the product-type ecosystem, the market reveals a clear hierarchy of functional demand. Dispersants continue to command the largest share of additive consumption, reflecting their critical role in maintaining engine cleanliness, suspending contaminants, and preventing sludge formation across high-mileage passenger and commercial platforms. Detergents follow closely, serving as essential alkaline components that neutralize acidic combustion byproducts and protect metal surfaces. Viscosity index improvers represent another cornerstone category, enabling multi-grade formulations that balance cold-start performance with high-temperature stability. Anti-wear agents, oxidation inhibitors, and corrosion inhibitors round out the essential functional suite, with each chemistry category experiencing distinct growth pressures tied to evolving engine designs and lubricant specification upgrades. Our full report delivers precise volume and revenue mappings across these categories, allowing procurement and R&D leadership to benchmark their portfolio exposure against market-wide demand signals.
Segmentation by vehicle type further illuminates consumption patterns. Passenger cars remain the dominant application channel, driven by global fleet expansion, replacement lubricant demand, and the rapid adoption of low-viscosity, fuel-efficient formulations. Heavy commercial vehicles constitute a substantial secondary demand pillar, particularly in regions where long-haul freight, mining, and construction activities sustain steady consumption of high-performance diesel engine lubricants. Light commercial vehicles occupy a growing mid-tier segment, increasingly influenced by urban delivery logistics, last-mile electrification transition timelines, and localized emissions enforcement. By connecting vehicle-type consumption profiles to regional economic indicators and regulatory calendars, our study enables clients to anticipate category-specific demand shifts rather than react to them.
Geographic Distribution and Regional Growth Vectors
The spatial distribution of additive demand reveals a structurally imbalanced but evolving global map. Asia Pacific continues to represent the largest regional consumption base, underpinned by dense automotive manufacturing networks, expanding middle-class vehicle ownership, and aggressive localization strategies by both multinational suppliers and domestic formulators. North America maintains a robust secondary market, shaped by mature vehicle parc dynamics, stringent OEM performance expectations, and ongoing reformulation activity surrounding latest-generation specifications. Europe occupies a strategically complex position, where decarbonization policies, OEM approvals, and premium lubricant positioning intersect with steady market consolidation.
Fuel Additives Market
Latin America and the Middle East and Africa, while smaller in absolute scale, offer distinctive growth narratives. The Latin American market reflects cyclical economic sensitivities but benefits from sustained commercial fleet activity and incremental modernization of lubricant standards. The Middle East and Africa region presents a dual profile: established demand in Gulf economies with strong automotive import markets, alongside emerging opportunity corridors in parts of Africa where infrastructure investment and vehicle parc growth are gradually lifting baseline lubricant consumption. Our full report contextualizes these regional profiles with historical trend analysis, capacity localization indicators, and supply-demand balance assessments—without relying on superficial aggregate figures—so that market entry, partnership, and sourcing decisions are grounded in structural reality rather than headline numbers.
Competitive Landscape and Strategic Positioning
The engine oil additives sector is characterized by high technical barriers, concentrated intellectual property, and a competitive field that blends global multinationals with regionally focused manufacturers. Market concentration metrics underscore this reality, with the top three players collectively accounting for approximately 62.45 percent of industry revenue and the top five firms extending their combined share to roughly 81.2 percent. This structural concentration signals both the importance of portfolio strength and the persistent pressure on smaller or regionally anchored participants to differentiate through specialty chemistries, cost-efficient manufacturing, or localized customer support.
At the center of the competitive field operate several globally recognized technology providers. The Lubrizol Corporation, headquartered in Wickliffe, Ohio, remains a major global supplier of additive packages for both passenger car and heavy-duty diesel engine oils. Its technology portfolio spans viscosity modifiers, dispersants, and anti-wear components, and its recent product activity illustrates the pace of specification-driven innovation: in mid-2025, Lubrizol introduced the PV1710 passenger car engine oil additive technology to help oil marketers meet ILSAC GF-7 performance requirements effective from March 2025 onward.
Infineum International Limited, based in Abingdon, UK, and structured as a joint venture between ExxonMobil and Shell, specializes in engine oil additive packages that balance fuel efficiency, emissions control, and protection against low-speed pre-ignition (LSPI). Afton Chemical Corporation, operating from Richmond, Virginia, develops and manufactures performance additives for engine oils with a notable emphasis on driveline and fuel additive integration. Chevron Oronite Company LLC, a subsidiary of Chevron and based in San Ramon, California, maintains a strong portfolio of lubricant and fuel additives under its OLOA branded products, with a global focus on OEM approvals and specification compliance.
European chemical giants further deepen the competitive fabric. BASF SE, headquartered in Ludwigshafen, Germany, supplies a broad range of lubricant additives, including antioxidants, dispersants, and viscosity index improvers tailored for automotive formulations. Evonik Industries AG, based in Essen, Germany, leads in viscosity index improvers and offers specialized additive solutions for fuel-efficient and high-performance automotive engine oils. LANXESS AG, from Cologne, Germany, provides antioxidants and extreme-pressure agents for engine oil applications, while Croda International Plc, located in Snaith, UK, contributes specialty additives including friction modifiers and bio-based components for modern automotive lubricants. Vanderbilt Chemicals, LLC, in Norwalk, Connecticut, rounds out the U.S.-based specialty presence with anti-wear, antioxidant, and extreme-pressure additives for engine oil and industrial lubricant formulations.
Worldwide Automotive Engine Oil Additives Market
The competitive picture also extends into Asia, where domestic manufacturing capacity and regional cost structures are reshaping supply dynamics. Jinzhou Kangtai Lubricant Additives Co., Ltd., based in Jinzhou, China, produces detergent and dispersant packages for automotive and industrial applications. Wuxi South Petroleum Additive Co., Ltd., situated in Wuxi, China, focuses on lubricant additives for automotive engine oils, including anti-oxidants and corrosion inhibitors. Tianhe Chemicals Group, also based in Jinzhou, operates as a large-scale producer of lubricant additive components and packages for global automotive engine oil markets. In Europe, BRB International B.V., a subsidiary of PETRONAS based in Ittervoort, Netherlands, supplies viscosity modifiers and engine oil additive packages, while Dorf Ketal Chemicals India Pvt. Ltd., operating from Mumbai, India, delivers specialty additives for fuel and lubricant performance in automotive engine oils. Together, these players illustrate a competitive arena where technology leadership, regional manufacturing footprints, and specification-compliance readiness determine market positioning.
Regulatory Catalysts, Raw Material Pressures, and Macro Trend Alignment
No analysis of the automotive engine oil additives market is complete without addressing the regulatory and macroeconomic forces that directly influence formulation requirements, cost structures, and demand velocity. The introduction of the ILSAC GF-7 specification, first licensed on March 31, 2025, represents one of the most consequential near-term drivers of additive innovation. Emphasizing enhanced fuel efficiency, reduced low-speed pre-ignition risk, and improved piston cleanliness for model year 2026 vehicles, GF-7 is accelerating demand for advanced additive packages capable of meeting stricter performance thresholds without compromising wear protection or oil durability.
Complementary regulatory activity has further shaped the compliance landscape. The American Petroleum Institute introduced the API SQ category in 2025 alongside ILSAC GF-7, addressing ultra-low viscosity grades not covered by GF-7. Both standards remain backward compatible with prior GF-6 and API SP formulations, a design choice that provides formulators with transition flexibility but also requires careful portfolio planning to avoid redundancy and ensure specification coverage across viscosity grades. In addition, API extended the overlap period for ILSAC GF-6 and ILSAC GF-7 engine oil standards to October 1, 2026, granting additional transition time for additive and oil formulations—a development that carries direct implications for inventory strategy, product launch sequencing, and supplier communications.
On the raw material front, the operating environment has grown more volatile. In early 2026, base oil and additive costs rose amid geopolitical tensions in the Middle East and persistent supply chain pressures. Multiple suppliers announced price increases of up to 15–20 percent on finished lubricants and components, underscoring the importance of proactive procurement planning, dual-sourcing strategies, and formulation optimization to protect margins. For additive manufacturers and lubricant marketers alike, cost volatility is not merely an input issue; it is a strategic variable that affects pricing power, competitive positioning, and customer retention.
Broader macro trends reinforce the direction of travel. Stricter global emissions regulations across the United States, the European Union, China, and India continue to mandate lower SAPS (sulphated ash, phosphorus, sulfur) engine oils, accelerating adoption of specialized additives for compliance. This regulatory momentum favors suppliers that can deliver high-performance, low-ash formulations and penalizes those that rely on older additive architectures. At the same time, the industry’s ongoing emphasis on fuel economy, engine durability, and emissions control is aligning additive development priorities with OEM expectations for next-generation powertrains, including turbocharged gasoline direct injection engines and advanced hybrid platforms.
Inside the Report: Operational Content and Decision-Ready Intelligence
Our Worldwide Automotive Engine Oil Additives Market research study is structured to translate market complexity into operational clarity. Rather than presenting data in isolation, the report embeds figures within analytical frameworks that support concrete business decisions. The publication covers historical performance tracking from 2020 through the 2025 base year, providing verified trend lines that contextualize the 2026–2032 forecast period. It then extends forward with demand projections, segmentation mapping, and scenario-aware commentary that help clients test strategic assumptions against plausible market outcomes.
The report systematically examines product-type, vehicle-type, and regional segmentation structures, giving readers a complete view of where demand is concentrated and how it is shifting. Beyond segment sizing, it evaluates the strategic implications of each split, highlighting which categories are most exposed to specification upgrades, which vehicle channels are most sensitive to economic cycles, and which geographies present the strongest mismatch between supply capacity and rising local demand. This layered approach allows clients to move from broad market awareness to targeted portfolio action.
Competitive intelligence forms another central pillar of the study. Company profiles, technology positioning, geographic footprints, and recent activity are synthesized into a comparative landscape that helps clients evaluate partnership opportunities, competitive threats, and benchmarking gaps. Recent developments—including new product launches, exhibition participation, specification updates, and regulatory milestones—are incorporated to ensure that the analysis reflects near-term market momentum rather than stale structural snapshots. For instance, the report captures the ILSAC GF-7 first licensing milestone, the API SQ category introduction, the GF-6/GF-7 overlap extension through October 2026, and key supplier announcements that signal where formulation innovation is heading.
Equally important, the study integrates raw material dynamics, cost pressures, and regulatory timelines into a unified narrative. This ensures that pricing strategy, sourcing decisions, and product roadmap planning are evaluated against the same operational reality. Clients gain a format that supports cross-functional alignment between R&D, procurement, sales, and executive leadership, reducing the friction that often occurs when market data is fragmented across multiple sources.
Strategic Value for 2026 Decision-Making
Portfolio Optimization and Specification Readiness
As ILSAC GF-7 and API SQ gain operational traction, companies must decide how to allocate development resources across viscosity grades, performance tiers, and regional compliance requirements. The report provides the contextual mapping needed to identify which product lines require reformulation urgency, which can be managed through backward-compatible extension strategies, and where transitional overlap periods create timing flexibility. This enables R&D and product management teams to sequence launches with greater confidence and reduce the risk of specification gaps.
Competitive Positioning and Supplier Strategy
Given the high market concentration and the technical sophistication of leading additive suppliers, procurement and strategy teams benefit from a clear view of who controls which technology domains, where regional manufacturers are scaling capacity, and how recent product and exhibition activity signals future competitive moves. Armed with this intelligence, organizations can negotiate from a stronger position, diversify sourcing where appropriate, and align partnership choices with long-term formulation roadmaps rather than short-term price considerations alone.
Cost Management in a Volatile Input Environment
With base oil and additive cost increases persisting into early 2026, margin protection has become a board-level concern. The study’s integrated treatment of cost dynamics, supply chain pressure points, and regional demand resilience supports more disciplined hedging, inventory planning, and formulation efficiency initiatives. Decision-makers can use the report’s frameworks to stress-test pricing strategies, evaluate make-versus-buy considerations, and identify segments where value-added performance can justify premium positioning despite input inflation.
Regional Expansion and Market Entry Planning
For organizations evaluating geographic expansion, the report offers the structural context needed to separate headline opportunity from operationally viable growth. Regional demand profiles, vehicle parc dynamics, regulatory calendars, and competitive density are analyzed together so that market entry, capacity allocation, and distribution partnership decisions are grounded in segment-level realism. This is particularly valuable for companies targeting fast-growing demand centers where local formulation preferences, approval pathways, and pricing norms differ materially from mature Western markets.
Regulatory Foresight and Compliance Alignment
The alignment between additive technology and evolving emissions and performance standards is now a core strategic variable. By mapping the implications of ILSAC GF-7, API SQ, SAPS reduction mandates, and OEM approval requirements, the report helps compliance, technical, and commercial teams synchronize their plans. Organizations that anticipate regulatory shifts early can secure first-mover advantages in specification adoption, reduce reformulation bottlenecks, and position themselves as reliable partners for OEMs and lubricant marketers navigating complex approval processes.
Conclusion: From Market Awareness to Strategic Execution
The Worldwide Automotive Engine Oil Additives Market is entering a phase where growth will increasingly be determined by specification readiness, formulation differentiation, and the ability to manage cost and supply volatility without losing competitive ground. The 3.21 percent CAGR projected through 2032 signals steady expansion, but the real value for 2026 decision-makers lies in understanding where within that growth curve the most defensible opportunities reside. Our full market research study provides the depth, structure, and competitive context required to convert macro trends into actionable strategy. For executives and technical leaders seeking to align product portfolios, sourcing strategies, and regional plans with the realities of a rapidly evolving lubricant ecosystem, this report offers a direct pathway from intelligence to execution. We invite you to access the complete study to explore the full segmentation analysis, detailed company assessments, forecast scenarios, and operational frameworks designed to support high-stakes decisions across the 2026–2032 horizon.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Engine Oil Additives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: HEA, HPA, HEMA, HPMA Market to Hit $2.19B by 2032, 5.28% CAGR (2026-2032)
By pmarketresearch, 2026-09-16
Strategic Horizons: Navigating the 2026 Landscape of HEA, HPA, HEMA, and HPMA Markets
Executive Overview
The global chemical landscape for hydroxy-functional acrylate and methacrylate monomers is entering a critical phase of recalibration. As we move through the mid-2020s, the Worldwide HEA, HPA, HEMA, and HPMA Market stands at a pivotal juncture, defined by shifting demand vectors, feedstock volatility, and strategic capacity adjustments among major producers. For executives and strategic planners, understanding the trajectory from 2026 through 2032 is not merely an academic exercise; it is a fundamental requirement for informed capital allocation and supply chain resilience.
This market research provides a comprehensive lens into the sector, capturing the transition from post-pandemic recovery stability to a new era of operational optimization. The narrative is no longer about simple growth but about navigating complexity. With the overall market size reflecting steady expansion over the historical period of 2020 to 2025, stakeholders are now looking toward the forecast period of 2026 to 2032 to capitalize on emerging opportunities while mitigating regulatory and input cost risks.
This introduction serves as a primer to the full study, highlighting the strategic value embedded within the data. It is designed to equip decision-makers with the context needed to understand why this intelligence matters now, without revealing the granular segmentation details that form the core of the proprietary analysis.
Market Trajectory and Macro Indicators
The historical performance of the hydroxy-functional monomers market demonstrates a consistent upward trend, reflecting the enduring utility of these chemicals across diverse industrial applications. From 2020 to 2025, the market experienced measured growth, driven by sustained demand in coatings, adhesives, and specialized medical applications. As we look forward to the forecast period extending to 2032, the momentum is expected to continue, supported by industrial development in key regions and the ongoing modernization of manufacturing processes.
2-Ethylhexyl Methacrylate (2-EHMA) Market
The projected compound annual growth rate over the forecast period indicates a healthy expansion trajectory. For corporate strategists, this implies that the sector remains attractive despite broader economic headwinds. However, growth rates alone do not tell the full story. The timing of revenue realization, the stability of supply chains, and the ability to manage input costs will differentiate the winners from the laggards. Our analysis delves into these temporal dynamics, offering a year-by-year breakdown that allows for precise budgeting and capacity planning.
It is crucial for stakeholders to recognize that these macroeconomic figures are underpinned by complex regional and application-specific drivers. While the top-line numbers suggest stability, the underlying composition varies significantly. Accessing the detailed segmentation within the full report is essential for companies seeking to align their specific product portfolios with the most lucrative growth pockets.
Core Operational Content and Scope
A robust market study must go beyond aggregate statistics to provide actionable intelligence. This report is structured to support detailed strategic planning across multiple dimensions of the business. The analysis covers the four primary chemical types that define this sector, providing a comparative view of their respective market positions and growth potentials. Understanding the nuances between these chemical variants is vital for procurement teams and R&D departments aiming to optimize formulations or identify alternative sourcing opportunities.
Furthermore, the study dissects the application landscape, recognizing that demand is not monolithic. Whether the focus is on industrial coatings, adhesive technologies, medical devices, or water treatment solutions, each vertical presents unique challenges and opportunities. The report details how consumption patterns differ across these sectors, influenced by factors such as regulatory changes, technological advancements, and end-user preferences. For instance, the medical and contact lenses segment requires a different strategic approach compared to the high-volume paints and coatings industry.
Geographic coverage is another cornerstone of this intelligence. The research maps out demand and supply dynamics across major global regions, highlighting where production capacity is concentrated and where consumption is rising fastest. This geographic granularity is essential for multinational corporations managing logistics and local compliance, as well as for investors looking to identify emerging markets before they become mainstream. The full document provides the specific regional valuations and growth rates necessary to build a fully localized strategy.
Competitive Landscape and Player Strategy
The market structure is characterized by a mix of established global chemical giants and specialized regional manufacturers. Analysis of the competitive field reveals a landscape where concentration is moderate, yet strategic consolidations are shaping the future. The industry is not purely commodity-driven; differentiation through purity, specialty grades, and supply reliability plays a significant role in market share retention.
Worldwide HEA, HPA, HEMA, & HPMA Market
Prominent players such as Dow Inc. and BASF SE maintain strong positions through extensive production capabilities and diversified portfolios. Dow, based in Midland, Michigan, remains a major global producer of HEA, HPA, HEMA, and HPMA monomers, leveraging its scale to serve coatings, adhesives, and resin markets. Similarly, BASF SE in Ludwigshafen continues to lead with a broad offering of HEA and HEMA specialty acrylates, recently reporting production expansions to secure supply continuity.
In the Asia Pacific region, Mitsubishi Chemical Group Corporation and Nippon Shokubai Co., Ltd. are key producers. Mitsubishi focuses on high-purity HEMA and HPMA, including grades tailored for electronics and photoresist applications, while Nippon Shokubai emphasizes high-purity and low-skin-sensitization variants for coatings and electronics. Evonik Industries AG and Röhm GmbH from Germany contribute significantly to the methacrylate segment, with Röhm offering HEMA and HPMA under its VISIOMER brand for reactive resins and adhesives.
Recent developments highlight the dynamic nature of this competition. Wanhua Chemical Group Co., Ltd. announced a significant capacity expansion in May 2025, increasing HEMA production capacity to 55,000 tons to meet demand. In contrast, BASF SE announced price increases in mid-2025 to offset rising energy and raw material costs, illustrating the divergent strategic levers companies are pulling. These moves underscore the importance of monitoring competitor actions closely; a capacity expansion in one region can shift global pricing power, while a price increase can accelerate demand for alternatives.
Industry Dynamics: Feedstock and Regulatory Pressures
Operational strategy in 2026 cannot be divorced from the external forces influencing cost structures and compliance requirements. The upstream feedstock environment is a critical variable for margin management. Acrylic acid, the primary upstream feedstock for HEA and HPA, saw US prices reach 1,260 USD per metric ton in August 2025. While this represented a month-over-month increase, it was down year-over-year, reflecting the volatile nature of petrochemical derivatives. Meanwhile, methacrylic acid, key for HEMA and HPMA, experienced a quarter-over-quarter price decline in North America in Q4 2025 due to weaker exports.
These fluctuations are part of a broader trend where global acrylic monomer markets faced downward price pressure in the second half of 2025 from new capacities and weak demand linked to propylene feedstock trends. For procurement leaders, this suggests a potential window for favorable contracting, but also the risk of supply disruptions if capacity adjustments lag behind demand shifts. Our report integrates these feedstock trends with monomer pricing models to help companies forecast their input costs more accurately.
On the regulatory front, the US EPA HON Rule imposes new emissions-control requirements on synthetic organic chemical manufacturing facilities. This introduces compliance costs and potential operational constraints for manufacturers within the region. However, temporary regulatory relief has been granted for certain stationary sources under Clean Air Act section 112(i)(4) for up to two years. Navigating these regulatory nuances is essential for maintaining operational continuity. Additionally, in the medical sector, Poly(2-hydroxyethyl methacrylate) used in devices such as contact lenses and urethral bulking agents remains subject to systematic biocompatibility reviews by the FDA. Literature on host responses and potential adverse effects continues to influence product design and safety standards, requiring manufacturers to stay aligned with evolving compliance expectations.
Strategic Imperatives for 2026 Decision Making
As enterprises plan for the remainder of the decade, several strategic imperatives emerge from the data. First, supply chain diversification is no longer optional. Given the concentration of production capacity in specific regions and the volatility of feedstock markets, relying on a single source or region exposes companies to undue risk. The report provides the visibility needed to identify alternative suppliers and assess their capability to meet quality and volume requirements.
Second, innovation in application technology offers a pathway to margin protection. As commodity pricing faces pressure from new capacities, differentiation through high-performance grades or specialized formulations can justify premium pricing. Companies that invest in R&D aligned with high-growth application segments, such as water treatment or specialized medical devices, will likely outperform those competing solely on volume.
Third, regulatory anticipation must be built into long-term planning. The interplay between emissions controls and temporary exemptions requires agile compliance strategies. Firms that proactively adapt their production processes to meet stricter standards while managing the associated costs will secure a competitive advantage. The full study includes scenario analysis to help leaders model the impact of regulatory changes on their operations.
Concluding Perspective
The Worldwide HEA, HPA, HEMA, and HPMA Market is poised for continued evolution. While the macro indicators suggest steady growth, the true value for decision-makers lies in the details hidden beneath the aggregate numbers. Understanding the specific dynamics of segmentation by type, application, and region is what transforms raw data into actionable strategy. The competitive moves by key players like Wanhua and BASF, combined with the shifting feedstock and regulatory landscape, create a complex environment where information asymmetry determines success.
This report is designed to close that information gap. By providing a detailed roadmap of the market from 2026 to 2032, it enables organizations to move from reactive positioning to proactive strategy. To gain access to the complete segmentation data, precise regional revenue figures, and the full competitive benchmarking analysis required to execute these strategies, stakeholders are encouraged to request the full publication. The insights contained within are critical for navigating the next phase of industry development with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide HEA, HPA, HEMA, & HPMA Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: WNT Signaling Inhibitors Market Reaches $1.45B in 2025; Forecasted to Hit $3.3B by 2032 at 12.5% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Next Decade: Inside the Worldwide Wingless and Integrated (WNT) Signaling Pathway Inhibitors Market
The pharmaceutical and biotechnology landscape is constantly reshaped by breakthroughs in molecular understanding. Among the most promising yet complex frontiers lies the Wingless and Integrated (WNT) signaling pathway. Targeting this pathway offers transformative potential for oncology, fibrotic diseases, and regenerative medicine. However, navigating the commercial realities of WNT signaling pathway inhibitors requires more than surface-level data. It demands rigorous, forward-looking analysis grounded in historical performance and predictive modeling. PW Consulting's latest Worldwide Wingless and Integrated (WNT) Signaling Pathway Inhibitors Market report delivers precisely that intelligence.
Worldwide Wingless and Integrated (WNT) Signaling Pathway Inhibitors Market
This comprehensive study examines market evolution from 2020 through 2032, presenting a detailed valuation framework that captures both retrospective growth and forward projections. The market stood at approximately 890.5 million USD in 2020, climbing steadily to 1445.66 million USD by 2025. Looking ahead, the projected trajectory indicates sustained expansion, with the market expected to reach 1725.68 million USD in 2026 and continue its upward march to 3297.12 million USD by 2032. This represents a compound annual growth rate of 12.5 percent, signaling robust demand drivers and deepening investment interest across the value chain.
Such figures are not abstract statistics. They reflect accelerating research activity, expanding preclinical pipelines, and the strategic positioning of key players who are actively shaping the supply ecosystem. Yet behind every headline number lies a nuanced architecture of drug classes, therapeutic applications, and regional dynamics that demand careful dissection. This report goes beyond top-line valuations to unpack the structural forces that will define competitive advantage through 2032.
A Multi-Dimensional Market Architecture
The WNT signaling pathway inhibitors market cannot be understood through a single lens. It is a composite ecosystem where drug modality, disease indication, and geographic reach intersect to create distinct value pools. Our analysis segments the market across three critical dimensions: drug class, therapeutic area, and geographic region. Each segmentation reveals unique growth mechanics and strategic implications for stakeholders operating in this space.
Drug Class Segmentation: The Battle Between Small Molecules and Biologics
Small molecule inhibitors currently command the largest share of the market landscape. Their widespread adoption in academic and preclinical research settings is driven by accessibility, established synthesis pathways, and the breadth of chemical tools available to investigators. Monoclonal antibodies and other biologic modalities represent a growing but more specialized segment. These agents offer distinct pharmacological profiles and are increasingly explored for targeted applications where precision modulation is required. Biologics and other emerging formats complete the triangulation, capturing niche but high-potential demand.
The interplay between these drug classes is far from static. As synthesis techniques mature and manufacturing capabilities scale, cost dynamics shift. Research-grade materials for complex multi-step synthesis pathways, particularly for Porcupine and Tankyrase inhibitors, currently range between 50 and 200 USD per milligram. This pricing structure influences procurement strategies, shapes the inventory decisions of research suppliers, and ultimately affects the pace at which new candidates can advance through discovery pipelines. Understanding these cost structures is essential for anyone evaluating supply chain resilience or forecasting demand elasticity.
Therapeutic Area Distribution: Oncology Leads, Fibrosis and Bone Disorders Follow
Oncology remains the dominant therapeutic anchor for WNT pathway inhibition. The biological rationale is compelling: dysregulated WNT signaling is implicated in tumor initiation, progression, and resistance mechanisms across multiple solid tumor types. Consequently, oncology-directed research and development activities account for the largest portion of market activity. Fibrotic diseases represent the second major cluster, reflecting growing recognition of WNT pathway involvement in tissue remodeling and chronic fibrosis. Bone and joint disorders, along with other indications, round out the therapeutic spectrum, each presenting distinct clinical needs and research priorities.
This therapeutic diversity is both a strength and a challenge. It diversifies revenue potential but also fragments focus. Companies must decide where to concentrate resources, which indications offer the clearest path to clinical validation, and how to align their product portfolios with emerging scientific consensus. Our report provides a structured framework for making these allocation decisions with confidence.
Worldwide Prostaglandins and Related Drugs Market
Regional Dynamics: North America Anchors, Global Markets Expand
Geographically, the market exhibits clear patterns of concentration and opportunity. North America continues to serve as the primary hub for research activity, supply chain infrastructure, and early-stage investment. Europe maintains a strong and stable presence, supported by well-established research institutions and a mature pharmaceutical ecosystem. The Asia Pacific region represents a dynamic growth zone, driven by expanding biotechnology capacity and increasing research expenditure. The Rest of the World segment, while smaller in absolute terms, offers emerging opportunities as global scientific collaboration intensifies.
Competitive Landscape: Research Suppliers and Emerging Clinical Players
The competitive terrain for WNT signaling pathway inhibitors is defined by a dual structure: a robust ecosystem of research-grade suppliers and a smaller but strategically vital cohort of companies advancing clinical-stage candidates. Understanding both layers is critical for anticipating market shifts and identifying partnership or acquisition opportunities.
Research-Grade Suppliers: The Foundation of Discovery
Several established chemical and biological supply companies form the backbone of the research supply chain. MedChemExpress LLC, headquartered in Monmouth Junction, New Jersey, supplies a broad range of research-grade WNT pathway inhibitors, including XAV939, a Tankyrase inhibitor, IWP-2, a Porcupine inhibitor, and ICG-001, a CBP inhibitor. Selleck Chemicals, based in Houston, Texas, offers a complementary portfolio featuring XAV939, IWR-1, KY02111, and Wnt-C59, catering to academic and industrial laboratories alike.
Cayman Chemical, located in Ann Arbor, Michigan, emphasizes high-purity inhibitor offerings such as IWP-L6 and JW55 for laboratory research applications. Tocris Bioscience, operating from Bristol, United Kingdom, markets selective WNT pathway modulators including XAV939 and IWP-2, alongside complementary agents like CHIR99021, which, while an activator, rounds out the research toolkit. Sigma-Aldrich, with its extensive catalog based in St. Louis, Missouri, distributes widely used inhibitors such as IWR-1-endo and IWP-3, leveraging its global distribution network to serve a broad research constituency. TargetMol, based in Boston, Massachusetts, sells a focused collection of WNT signaling inhibitors including ETC-159, a Porcupine inhibitor, RXC004 analogs, and Tankyrase inhibitors specifically curated for preclinical studies.
These suppliers operate in a market where products are labeled for research use only, meaning they are not approved for diagnostic or therapeutic applications. This regulatory reality shapes purchasing behavior, limits commercialization pathways for the suppliers themselves, and reinforces the early-stage nature of the current market. Yet it also creates a stable, recurring demand stream driven by the relentless pace of basic and translational research.
Clinical-Stage Developments: The Horizon of Therapeutic Translation
While no WNT signaling pathway inhibitor has yet received FDA approval for therapeutic use, the clinical pipeline tells a story of accelerating ambition. Over 100 active clinical trials target WNT pathway modulation, with oncology representing the primary focus. This volume of investigative activity signals strong scientific conviction and significant unmet need.
Redx Pharma has emerged as a notable example of clinical ambition in this space. In October 2022, the company announced the first patient dosed in a Phase 1b/2 trial of its Porcupine inhibitor RXC004 in combination with gemcitabine and nab-paclitaxel for advanced pancreatic cancer. Just two months later, in December 2022, Redx Pharma reported another milestone: the first patient dosed in a Phase 1b/2 trial of RXC004 combined with atezolizumab and bevacizumab for advanced solid tumors. These developments illustrate the strategic logic of combination approaches and the broadening exploration of WNT inhibition across difficult-to-treat malignancies.
Such clinical milestones, while early-stage, materially influence market sentiment and investor interest. They validate the biological target, encourage further capital allocation, and stimulate competitive responses from other biotechnology firms considering entry into this pathway. The report tracks these developments in detail, mapping them against broader pipeline trends to provide a realistic view of commercialization timelines and risk factors.
Market Dynamics: Navigating Regulatory and Economic Realities
The WNT signaling pathway inhibitors market operates within a complex set of constraints and opportunities. Regulatory frameworks currently classify WNT pathway inhibitors as research-use-only products, prohibiting their deployment in diagnostic or therapeutic settings. This classification is not merely a legal footnote; it fundamentally shapes market structure, pricing dynamics, and the strategic options available to suppliers and developers alike.
From a reimbursement perspective, the research-use designation means that traditional healthcare reimbursement pathways do not yet apply. Value capture happens through research procurement, institutional budgets, and grant-funded purchasing rather than through payer-driven markets. This dynamic favors suppliers with strong institutional relationships, reliable quality controls, and competitive pricing models. It also means that the transition from research-grade supply to therapeutic commercialization will represent a structural market shift, potentially reshaping competitive hierarchies and value distribution.
On the supply side, the complexity of multi-step synthesis for Porcupine and Tankyrase inhibitors creates inherent cost pressures. Prices ranging from 50 to 200 USD per milligram for research quantities reflect the technical demands of production, purity requirements, and scale limitations. These cost structures influence procurement decisions and serve as a barrier to rapid scaling for some modalities. Companies that can optimize synthesis pathways, secure reliable raw material inputs, or develop more efficient manufacturing processes will gain meaningful competitive advantages.
Despite these constraints, the sheer volume of clinical investigation underscores the market's underlying potential. Over 100 active trials signal sustained scientific interest and a willingness to navigate the regulatory and biochemical challenges associated with WNT pathway modulation. The concentration of market activity further highlights the role of a relatively small group of players. The top three companies account for 42.5 percent of market revenue, while the top five hold 58.8 percent. This concentration indicates that strategic positioning, supply reliability, and product portfolio breadth are significant differentiators in a market where scale and trust matter.
What the Report Delivers: Actionable Intelligence for 2026 and Beyond
This market research report is designed for decision-makers who need more than aggregated numbers. It provides a structured, evidence-based platform for strategic planning across multiple functional domains.
The report opens with a detailed market overview and valuation framework, establishing baseline metrics and growth trajectories that anchor all subsequent analysis. It then proceeds through a comprehensive segmentation analysis, examining drug class performance, therapeutic area adoption patterns, and regional distribution dynamics. Each segment is evaluated for growth drivers, constraints, and prospective shifts through the 2032 forecast horizon.
Competitive landscape assessment forms a central pillar of the report. Detailed company profiles cover research suppliers, their product portfolios, headquarters locations, and strategic positioning. The analysis extends to clinical-stage developments, tracking trial phases, combination strategies, and therapeutic targets that are shaping the future commercial landscape. Recent developments, including Redx Pharma's Phase 1b/2 trial initiations, are contextualized within broader pipeline activity to illustrate the pace and direction of clinical translation.
Market dynamics are explored through multiple lenses: regulatory status and its implications for commercialization pathways, reimbursement realities for research-use products, raw material cost structures and their impact on pricing and supply resilience, and the concentration of market value among leading players. The report also addresses frequently asked questions that arise in executive discussions, providing clear, defensible answers grounded in data and regulatory documentation.
Forecasting methodology is transparent and rigorous. The report covers historical performance from 2020 through 2025 and extends projections through 2032, applying a compound annual growth rate of 12.5 percent within a structured scenario framework. All valuations are expressed in USD million, ensuring consistency and comparability for international audiences. Decision-makers can use these projections to model capacity investments, prioritize research and development allocation, evaluate partnership opportunities, and stress-test strategic assumptions against evolving market conditions.
Why This Analysis Matters for 2026 Decision-Making
The year 2026 represents a pivotal inflection point for the WNT signaling pathway inhibitors market. Historical growth has been steady, but the forward trajectory suggests an acceleration driven by deepening scientific understanding, expanding clinical investigation, and maturing supply chain capabilities. Organizations that act on reliable intelligence today will be better positioned to capture value as the market transitions from a predominantly research-focused ecosystem toward broader therapeutic and commercial applications.
For research suppliers, understanding segment growth rates, regional demand patterns, and cost dynamics is essential for optimizing inventory, pricing, and geographic expansion. For biotechnology and pharmaceutical companies, mapping the competitive landscape and clinical pipeline provides critical input for portfolio strategy, partnership targeting, and risk assessment. For investors and financial analysts, the combination of historical valuations, forward projections, and concentration metrics offers a robust basis for evaluating market attractiveness and identifying high-potential sub-segments.
The strategic value of this report lies in its ability to translate complex, multi-layered market data into actionable insights. It does not merely describe where the market has been; it illuminates the structural forces that will determine where it goes. By integrating historical data, segmentation analysis, competitive profiling, and regulatory context, the report equips stakeholders with the clarity needed to make informed, forward-looking decisions.
Get the Complete Intelligence
This overview provides a foundation, but the full strategic picture requires depth. The complete report delivers exhaustive segmentation data, granular company assessments, detailed forecast models, and comprehensive regulatory and reimbursement analysis. Every figure, trend, and strategic recommendation is sourced and verifiable, ensuring that your decisions rest on solid analytical ground.
Do not navigate the WNT signaling pathway inhibitors market with fragmented data or assumptions. Access the full Worldwide Wingless and Integrated (WNT) Signaling Pathway Inhibitors Market report to unlock the detailed intelligence you need. Explore the complete segmentation breakdowns, examine the competitive landscape in full, and leverage the 2032 forecast to shape your strategy with confidence. The market is moving. Make sure your decisions are informed by the most comprehensive analysis available.
For detailed analysis of this topic, please visit the official page: Worldwide Wingless and Integrated (WNT) Signaling Pathway Inhibitors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com